For more than a century, the media occupied a distinctive position in the organization of modern societies. They did more than transmit information or broadcast programmes. They largely determined what deserved to be seen, heard or discussed. Newspapers organized the news, radio accompanied everyday life, and television brought millions of people together around the same images. Behind this cultural and political influence stood a relatively coherent economic architecture: the companies producing content also controlled, directly or indirectly, the channels through which it reached the public.
That architecture is coming apart.
The printed press faces declining circulation and advertising revenues. Television networks are gradually losing their central position in audiovisual consumption. Radio stations must compete for attention with podcasts and music streaming services. News agencies see their reporting circulate through digital environments whose rules and remuneration they do not control. Meanwhile, major media groups are discovering that their size, catalogues and established brands are no longer sufficient to guarantee their influence.
The paradox is considerable. Never have societies possessed so many means of producing, distributing and accessing content. Never have images, commentary and information circulated so rapidly. Yet some of the institutions that built the modern information economy are increasingly struggling to finance their operations.
This crisis is therefore not simply the decline of older technologies. It reveals a redistribution of value and power between those who produce content, those who organize its circulation and those who control access to audiences.
A Model Built on Scarcity
To understand the depth of this transformation, it is necessary to return to the economic logic that sustained legacy media for decades.
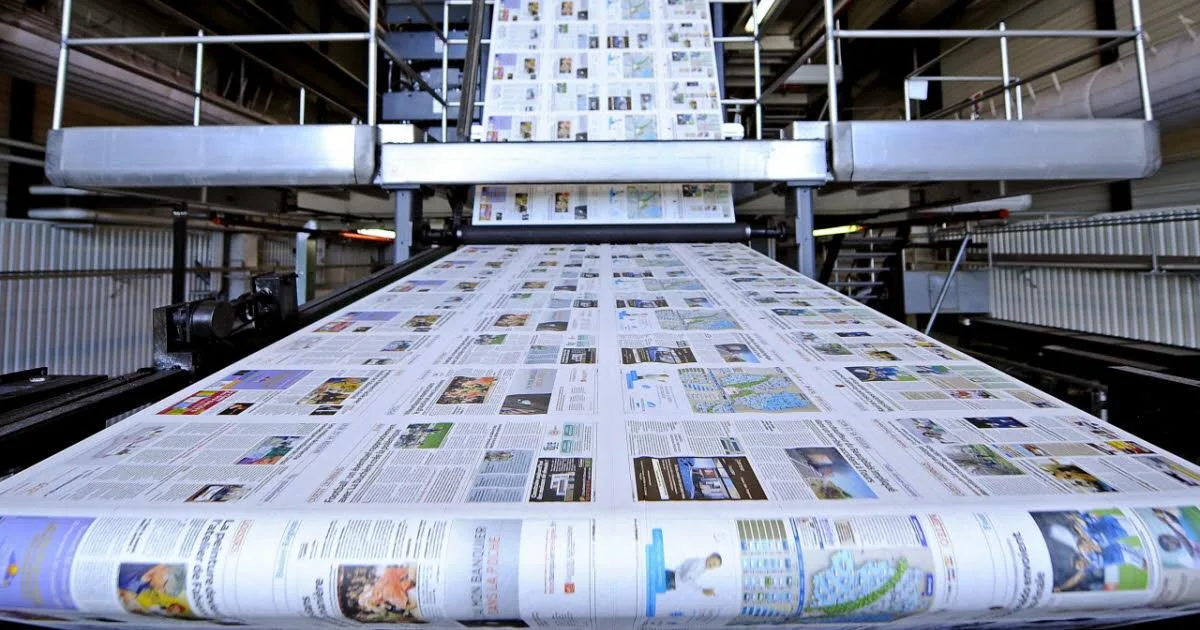
Printed newspapers depended on costly industrial infrastructure: printing presses, distribution networks, newsrooms, correspondents and commercial operations. Television required broadcasting frequencies, transmission equipment, studios and licences. Radio faced comparable technical constraints. These barriers limited the number of organizations capable of reaching large audiences.
Scarcity in distribution created economic value. A daily newspaper with a loyal readership could sell both copies and advertising space. A television channel attracting millions of viewers could sell access to that audience to advertisers. Media companies thus maintained a dual commercial relationship: they sold content to audiences and access to those audiences to businesses.
The system had its weaknesses. It depended on advertising cycles, industrial investment and, in some countries, public intervention. It also encouraged concentration, since economies of scale allowed large companies to spread their costs across substantial audiences.
But it possessed one decisive advantage: content producers and broadcasters retained considerable influence over the commercial conditions under which their work was distributed.
The internet gradually eliminated that scarcity without eliminating production costs.
Creating a website, publishing a video or distributing an audio programme became technically accessible to countless participants. Producing an extensive investigation, maintaining an international network of correspondents or financing an ambitious television drama, however, still requires capital, expertise and time.
Digital abundance has therefore separated two realities that were once closely connected: the ease of distribution and the difficulty of production.
Legacy media have lost part of the economic advantages associated with their infrastructure, while new intermediaries have developed advantages of a different kind, based on data, algorithms, user networks and control over digital interfaces.
Advertising Has Found a New Destination
The transformation of the advertising market is one of the most powerful mechanisms behind this crisis.
Under the traditional model, advertisers essentially purchased space associated with a particular media outlet and its audience. A newspaper page, a television commercial break or a radio advertisement offered access to groups of consumers whose characteristics were estimated through audience research.
Digital platforms fundamentally changed this logic. They made it possible to target users, measure certain interactions and adjust campaigns rapidly. Advertisers no longer purchase only the audience of a publication or programme; they purchase distribution, segmentation and optimization capabilities.
In the United States, according to the Interactive Advertising Bureau and PwC, internet advertising revenues reached $294.6 billion in 2025, compared with $258.6 billion in 2024, an increase of 13.9%. These figures cover the entire American digital advertising market and should not be equated exclusively with the revenues of major platforms. They nevertheless illustrate the scale of the market towards which advertising expenditure has shifted.
This evolution does not mean that every traditional media company is simultaneously losing every source of revenue. Some groups have developed profitable digital businesses, specialized commercial offerings or robust subscription models. But the shifting centre of gravity in advertising is changing their prospects.
The costs of editorial production remain largely with publishers, while the commercialization of attention can increasingly be handled by companies external to that production.
A journalistic investigation may require several weeks of work. A platform can subsequently capture part of the attention generated by its distribution without having incurred comparable editorial expenditure. This asymmetry is not universal: platforms themselves finance considerable infrastructure, and certain remuneration agreements exist. Nevertheless, it remains central to understanding the economic vulnerability of many news producers.
The problem is no longer simply how to sell enough advertising. It is how to determine what proportion of the value created by content returns to its producer.
Audiences Are Not Disappearing. They Are Moving.
The crisis of legacy media is sometimes presented as the consequence of declining public interest in information. That explanation is insufficient.
People continue to seek news, analysis, images and commentary. What is changing is where and how they consume them.
The Reuters Institute's Digital News Report 2026 describes the growing importance of video platforms and independent creators in access to news. Its survey indicates that 27% of respondents encountered content from news-focused creators during the previous week. The proportion rises to 46% when general-interest creators who occasionally discuss current affairs are included. These measures do not exclusively describe regular news consumption, nor do they mean that these audiences have abandoned traditional media.
In the United States, a Pew Research Center survey conducted in August 2026 found that 59% of adults said they obtained news from social media at least occasionally. Facebook and YouTube occupy important positions in these habits, while Instagram and TikTok contribute to the diversification of news distribution.
These transformations particularly affect the relationship between generations and media brands.
For decades, the identity of a newspaper or television channel served as the gateway to information. Readers purchased a publication, viewers selected a channel, and listeners tuned in to a station. The brand came before the content.
In algorithmic environments, that relationship can be reversed. Users discover a video, a commentary or a post before knowing who produced it. Content arrives through recommendations, sharing or search. The identity of its source sometimes becomes secondary, or even invisible.
The consequence is industrial as much as cultural: loyalty to a media organization is increasingly replaced by loyalty to an interface, a personality or a particular consumption experience.
A newspaper can therefore reach millions of people without establishing a direct relationship with them. It may enjoy considerable visibility while remaining exposed to changes in algorithms, formats and distribution conditions.
Audience size no longer guarantees control over the audience.
Television Loses Its Privileged Position
Television provides a particularly clear illustration of this transformation.
For decades, it enjoyed an exceptional position: it simultaneously organized programme distribution, scheduling and much of the associated advertising financing. Television networks possessed a rare ability to gather mass audiences around major events, news broadcasts, series and entertainment.
The arrival of on-demand video fragmented this organization.
Netflix, Disney+, Prime Video, YouTube and other services operate different business models, but share one characteristic: they allow audiences to consume content without necessarily following the schedules of traditional television channels.
This freedom changes the economics of broadcasting. A linear television channel must finance a programme schedule, maintain distribution capacity and bear substantial operating costs. When its audience contracts, some of those expenses do not decline proportionately.
Digital services face different constraints. They must finance catalogues, technical infrastructure, rights and subscriber acquisition. Competition for exclusive content long encouraged escalating investment, before the pursuit of profitability led several groups to impose greater financial discipline.
Streaming is therefore not a straightforward replacement of a failing model with a universally profitable one. It represents a different economic organization, with its own fixed costs, economies of scale and concentration risks.
Traditional broadcasters nevertheless retain significant advantages. Sporting events, major national occasions, certain live programmes and public-service news continue to create shared experiences. In several markets, television remains central to the media consumption of substantial population groups.
The rupture lies not in its immediate disappearance, but in the loss of its monopoly over mass audiovisual experiences.
The Press Faces a More Difficult Equation
For newspapers, the transformation is particularly challenging because it simultaneously affects their two principal historical revenue sources.
Print circulation is declining in many markets, while advertisers have access to a wider range of digital alternatives. The industrial costs of paper, printing and distribution cannot easily be reduced at the same pace as circulation volumes.
The digital transition generates new revenues, but their distribution remains uneven.
According to WAN-IFRA's World Press Trends Outlook 2024–2025, based on responses from more than 240 media executives across 85 countries, combined print circulation and print advertising revenues accounted for less than half of total revenues among responding organizations for the first time in the survey series.
This development reveals genuine diversification in business models. It does not, however, mean that digital revenues compensate everywhere for losses in traditional activities.
Subscriptions work particularly well when media organizations possess recognized brands, differentiated content and audiences able to pay. They can support business journalism, specialized investigations and international analysis. But local and general-interest media, or publications operating in markets with limited purchasing power, face different challenges.
The system therefore risks encouraging economic polarization.
On one side, powerful brands can deepen direct relationships with subscribers, invest in their products and consolidate their positions. On the other, smaller newsrooms may become dependent on platforms, institutional funding, philanthropic support or unstable commercial revenues.
The risk extends beyond the disappearance of individual publications. It also concerns reduced coverage of subjects that lack an immediately profitable market: municipal affairs, local administration, justice, public policy, remote communities and lengthy investigations.
A society can possess an abundant supply of information while suffering from insufficient journalistic production in essential areas.
News Agencies and the Invisible Value of Information
The position of news agencies adds another dimension to the crisis.
International and national news agencies occupy a fundamental place in the information production chain. They maintain correspondent networks, verify events, produce dispatches, photographs and videos, and supply this material to media organizations and other professional clients.
Their business depends heavily on trust, speed and continuity of service. Yet their production is often less visible than that of the outlets which reproduce it.
In a digital environment where information circulates instantaneously, this position creates a contradiction. Gathering and verifying information retain substantial value, but the resulting material can be reproduced, summarized, commented upon or redistributed across multiple interfaces.
Artificial intelligence potentially intensifies this tension by enabling services to generate summaries from existing content. Licensing agreements can create new revenues, but they do not automatically resolve questions of traceability, competition and remuneration.
News agencies therefore reveal a broader problem: infrastructure essential to the functioning of global information can find its economic value increasingly negotiated by actors far removed from the original journalistic work.
Power Changes Hands
The most important transformation cannot be measured solely in revenues or audience figures. It concerns the ability to determine the conditions under which information circulates.
Historically, major media organizations performed a selection function. They chose subjects, organized their presentation and determined their prominence. This power was imperfect, sometimes concentrated and frequently contested, but it belonged primarily to identifiable editorial institutions.
Digital platforms introduce a different form of intermediation.
They do not necessarily produce the information they distribute, but they control the mechanisms through which it is discovered. Recommendation systems, search engines, moderation policies and advertising formats directly influence content visibility.
This does not mean that all platforms exercise identical control or that they entirely replace editorial decisions. Their models, obligations and practices differ considerably.
Their influence nevertheless rests on a shared capability: organizing access to immense volumes of content produced by others.
This shift creates strategic dependence for media organizations.
A change in search rankings can affect a website's traffic. An adjustment to video recommendations can alter a channel's visibility. A new revenue-sharing policy can transform the profitability of an editorial activity.
Media companies no longer negotiate solely with advertisers, subscribers or traditional distributors. They must operate within digital infrastructures whose design and evolution they do not control.
This dependence becomes particularly significant when a small number of platforms concentrate a substantial share of the gateways to information.
Competition policy consequently becomes inseparable from media pluralism. A wide diversity of producers does not necessarily guarantee an equivalent diversity of distribution channels.
Artificial Intelligence Opens Another Front
The arrival of generative artificial intelligence transforms an already established crisis into a question about the very position of content producers.
Search engines traditionally acted as intermediaries between users and news websites. They directed audiences towards pages where publishers could offer subscriptions, display advertising or build lasting relationships.
Conversational interfaces introduce a different possibility: answering questions directly by synthesizing information drawn from multiple sources.
The change may appear subtle, but its economic implications are substantial.
When users obtain satisfactory answers without visiting the publications that contributed to them, the practical value of information can become further separated from the revenues received by its producers.
The actual effect will depend on user behaviour, citation mechanisms, commercial agreements, intellectual property rules and the ability of media organizations to offer content that automated answers cannot replace.
Artificial intelligence can also reduce certain costs. Transcription, translation, archive indexing, documentary research and some audiovisual production tasks can be accelerated. These efficiencies may help financially constrained newsrooms maintain or expand their activities.
But lower costs do not guarantee higher quality or a fair distribution of value.
The proliferation of automatically generated content may intensify competition for attention, complicate source identification and increase the importance of verification.
The paradox becomes sharper: technologies capable of producing and summarizing content at scale may increase the social value of reliable information while weakening some of the mechanisms that finance its production.
A Crisis of Work and Creativity
Media restructuring affects more than shareholders and management teams. It transforms professions.
Journalists are frequently expected to produce material for several formats. Audiovisual reporters increasingly become editors, presenters or digital content creators. Newsrooms integrate skills in data, search optimization, video, audience analytics and social distribution.
Such versatility can encourage innovation, but it can also increase workloads and reduce the time devoted to research, verification and investigation.
In audiovisual production, pressure on budgets, volatile commissioning and changing broadcaster strategies affect independent producers, technicians and writers. Automation tools introduce new possibilities while raising questions about remuneration and rights.
The crisis therefore possesses a social dimension that is often less visible than major consolidation deals.
When a newsroom closes a regional bureau, more than a budget item disappears. Reporting capacity, local knowledge and networks of sources may also be lost.
These capabilities are not automatically restored when economic conditions improve.
Editorial infrastructure can be dismantled quickly. Rebuilding it may take years.
Europe Between Protection and Adaptation
Europe presents a distinctive configuration, characterized by the importance of public-service media, cultural production support mechanisms and comparatively extensive regulation in several areas.
Film and audiovisual financing systems, obligations imposed on certain broadcasters, press subsidies and digital regulations seek to preserve national or European production capabilities.
Such intervention reflects an economic reality: some content possesses cultural, linguistic or democratic value that is not fully reflected in its commercial profitability.
But protection mechanisms face their own limitations.
Public support can preserve production diversity without resolving distribution problems. Financing obligations can help sustain an audiovisual industry without guaranteeing audience loyalty. Regulation can govern relationships between platforms and publishers, but its effectiveness depends on enforcement and technological developments.
The European question therefore goes beyond the opposition between markets and public intervention.
It concerns how to maintain independent production and distribution capacity in an environment where the infrastructure providing access to audiences is largely international.
France illustrates this tension particularly clearly. Its cultural financing system, public broadcasting sector and press support mechanisms provide instruments of cultural continuity. Yet they coexist with rapidly changing consumption habits and global competition for attention.
The challenge is not to recreate the conditions of the past artificially, but to determine which functions deserve preservation and which models can sustain them.
Different Vulnerabilities in Emerging Economies
The crisis does not unfold identically everywhere.
In economies where advertising markets are narrow and household incomes limited, digital subscriptions can hardly provide a universal solution. Media organizations often contend with high production costs relative to revenues, fragmented linguistic markets and substantial dependence on advertisers or institutional financing.
In several African, Asian and Latin American countries, mobile platforms represent both an extraordinary distribution opportunity and a new source of dependence.
They allow local producers to reach national, regional or diaspora audiences without maintaining costly traditional infrastructure. But the revenues associated with those audiences remain dependent on monetization conditions, advertising purchasing power and rules established by intermediaries.
Expanding digital access does not therefore automatically create a financially robust local media industry.
Language further accentuates these differences. Content distributed in major international languages can reach enormous markets, while productions intended for smaller linguistic communities face different commercial prospects.
This raises a question of cultural sovereignty: can a society sustainably preserve its ability to produce information and creative works in its own languages if distribution revenues are largely determined by external infrastructures?
Concentration as Both a Response and a Risk
Faced with fragmented audiences and pressure on margins, media groups pursue economies of scale.
Mergers, acquisitions, newsroom consolidation, catalogue integration and platform combinations follow an understandable logic. Companies seek to spread costs, strengthen technological capabilities, improve bargaining power and consolidate revenues.
But this response can generate a contradiction.
Concentration may improve the economic viability of some organizations while reducing the number of independent actors. It may also increase the influence of owners whose interests extend beyond the media sector.
Media ownership is not a new question. Industrial, financial and family groups have long occupied important positions in the industry. What is changing is the environment in which that ownership operates.
As traditional revenues decline, dependence on external financing may increase. When a media organization is no longer sufficiently profitable to sustain its activities independently, its survival may depend on a shareholder willing to accept lower returns or pursue other economic objectives.
It would be excessive to conclude that every media outlet owned by a diversified group loses its independence. Editorial safeguards, governance rules and professional cultures matter. But financing conditions inevitably influence organizations' room for manoeuvre.
The economic crisis of media can consequently become a crisis of institutional autonomy.
Trust Cannot Be Declared into Existence
The multiplication of information sources has not eliminated the question of trust. It has made it more complex.
Under the traditional system, media brands benefited from authority built through their history, visibility and professional practices. That authority could be challenged, but it rested on relatively stable institutions.
Digital environments give greater prominence to individual personalities, communities and direct relationships between creators and audiences.
This development has positive dimensions. It enables new voices to emerge, challenges certain editorial monopolies and opens access to perspectives that were previously marginalized.
But it also transforms the mechanisms of credibility.
A piece of content's popularity, rapid circulation or the perceived closeness of its author does not guarantee its accuracy. Conversely, belonging to an established media institution does not guarantee the quality of every publication.
Trust must therefore be understood as the outcome of verifiable practices: source transparency, correction of errors, separation of facts from opinions, methodological independence and the ability to acknowledge uncertainty.
In an environment saturated with information, these practices may become a competitive advantage. But their commercial value will depend on audiences' willingness to recognize and finance them.
This is one of the industry's central contradictions: what is expensive to produce is not necessarily what attracts the greatest attention.
The Models That May Survive
The disappearance of legacy media is neither inevitable nor uniform. Several paths of transformation are already visible.
Groups with powerful brands can deepen direct relationships with readers and subscribers. Specialized publications can develop professional offerings based on expertise, data and analysis. Audiovisual broadcasters can capitalize on live events, catalogues and production capabilities. Local media can strengthen their relevance by covering realities insufficiently addressed by major platforms.
Revenue diversification offers another path. Subscriptions, advertising, licensing, events, professional services, partnerships and audience contributions can form hybrid business models.
None of these solutions works independently of context.
Subscriptions require a sufficiently differentiated editorial proposition. Events demand an engaged community. Licensing requires negotiating capacity. Advertising depends on commercially valuable audiences. Public financing requires transparency and independence safeguards.
The decisive factor may become less the size of a media organization than its ability to maintain an identifiable, durable and economically viable relationship with its audience.
Companies whose content is easily substitutable risk remaining exposed to competition from platforms and automation. Those possessing distinctive expertise, established trust or loyal communities may retain advantages.
This is not a guarantee of success, but a shift in the conditions of competitiveness.
What Is Actually Disappearing
The expression "media crisis" sometimes suggests a general disappearance. The reality is more nuanced.
Television is not disappearing, but it no longer organizes audiovisual consumption alone. Newspapers are not disappearing, but their historical industrial model is losing some of its coherence. Radio is not disappearing, but it must share audio consumption with new formats. News agencies are not becoming obsolete, but the conditions under which their work generates value are changing.
What is weakening is an economic order in which production, distribution and monetization were sufficiently integrated to sustain powerful media institutions.
In its place is emerging a more fragmented system in which content producers, platforms, advertisers, independent creators and technology providers continuously negotiate the distribution of value.
This new environment can encourage an extraordinary diversity of expression and formats. It can also concentrate distribution power within a limited number of global infrastructures.
The two developments are not contradictory. An abundance of producers can coexist with a concentration of intermediaries.
That is precisely what distinguishes the current transformation from previous media revolutions.
Printing, radio and television each created new industries around relatively identifiable means of distribution. The digital economy separates these functions more extensively: producing, hosting, recommending, distributing, measuring and monetizing content can all fall to different companies.
The value of content no longer depends solely on its quality or potential audience. It also depends on the technical and commercial conditions under which it becomes visible.
A Question for Society
The crisis of legacy media cannot be reduced to defending companies confronted with changing markets. Industrial transformations are normal, and no technology possesses a permanent entitlement to profitability.
But information is not a product entirely comparable to others.
An investigation into corruption, independent coverage of institutions, verified local reporting or journalism from a conflict zone produces collective benefits extending beyond the commercial transaction between a media organization and its audience.
Markets can reward these activities, but they do not guarantee that they will be financed everywhere, on a sufficient scale.
This distinction explains why the crisis raises questions beyond competition between companies. It affects societies' ability to understand their own institutions, preserve spaces for debate and access independent sources of information.
The objective is not to protect every established actor indiscriminately. Some failed to adapt, others maintained excessively costly structures or underestimated changes in consumption. New entrants have also delivered genuine innovation and expanded access to public expression.
The question is rather how to preserve the essential functions of information within an economic system that does not necessarily remunerate them according to their collective usefulness.
The future of media will therefore not be decided solely in newsrooms or studios. It will also depend on competition rules, remuneration systems, technological infrastructure, cultural policies and audience choices.
For decades, owning a newspaper, a broadcasting frequency or a television channel meant controlling a privileged route into society. Today, content can circulate everywhere without its producers necessarily controlling its destination or economic value.
Legacy media are not merely losing a business model. They are losing a position in the organization of the world.
And the question that remains is not whether societies will continue to consume information. They will, in ever more numerous forms. It is who will still possess the resources, independence and responsibility to produce it.
Main Sources
- Reuters Institute for the Study of Journalism, Digital News Report 2026, University of Oxford.
- Reuters Institute for the Study of Journalism, Digital News Report 2025, University of Oxford.
- Interactive Advertising Bureau and PwC, Internet Advertising Revenue Report: Full Year 2025, April 2026.
- WAN-IFRA, World Press Trends Outlook 2024–2025, January 2025.
- Pew Research Center, Social Media and News Fact Sheet, October 2026.
Methodological note: The figures used in this analysis cover different geographical markets and survey populations. Findings from the United States are not extrapolated to the global media industry. Structural interpretations and forward-looking assessments represent Atlas Limits' editorial analysis and are distinguished from statistical findings attributed to the cited sources.
Atlas Limits Research Desk
Atlas Limits’ editorial and analytical desk.