Globalization has created remarkably efficient production networks, but some of their most critical stages have become exceptionally difficult to replace. A study published by the Bank for International Settlements on October 26, 2026, explains why industrial concentration does not always translate into strategic vulnerability—and why different dependencies require fundamentally different responses. From rare earths and semiconductors to artificial intelligence infrastructure, a central question is emerging: who actually holds the power to interrupt global production?
Globalization Has Created Dependencies We Still Struggle to Understand
For decades, global value chains were organized around a relatively straightforward principle: manufacture each component wherever production conditions were most economically advantageous.
Companies distributed their operations across continents, pursued economies of scale, concentrated specialized activities in industrial clusters, and reduced costs by optimizing their supply networks.
This model profoundly transformed the global economy.
It lowered production costs, accelerated technological diffusion, and enabled the emergence of manufacturing powers capable of supplying entire industries.
But it also created an industrial geography in which certain countries, companies, and sometimes individual facilities occupy positions of extraordinary importance.
The pandemic, trade tensions, export restrictions, and natural disasters have gradually exposed the vulnerabilities embedded in this architecture.
Since then, industrial sovereignty, economic security, diversification, and reshoring have become central elements of government strategies.
Yet one fundamental difficulty remains: not all dependencies create comparable risks.
A factory temporarily shut down by a natural disaster presents a different challenge from a technology whose production is almost entirely controlled by one country.
A geographically concentrated raw material is not necessarily irreplaceable.
Conversely, a component representing a negligible fraction of a product's total value may be sufficient to halt its entire production.
This distinction lies at the heart of a study published on October 26, 2026, by the Bank for International Settlements.
In Chokepoints in Global Supply Chains: Lessons from Rare Earths and Hard Disk Drives, Ryan Niladri Banerjee, Michael Chui, and Leonardo Gambacorta examine two situations that appear similar but are fundamentally different: China's concentration of industrial capabilities in rare earth supply chains and the disruption of global hard disk drive production caused by Thailand's 2011 floods.
Their comparison leads to an essential conclusion: industrial resilience depends not only on the degree of supply chain concentration but also on the nature of the capabilities involved, their substitutability, and the likely duration of disruptions.
This distinction fundamentally changes how economic security should be understood.
Real Dependency Begins Where Substitution Becomes Impossible
Industrial concentration is frequently measured through market shares.
When a country produces 70%, 80%, or 90% of a particular raw material, that dominance is generally interpreted as a strategic dependency for its trading partners.
But this interpretation remains incomplete.
Concentration becomes a genuine chokepoint when several conditions converge.
First, the activity must be indispensable to the functioning of a production chain.
Second, available alternatives must be insufficient, prohibitively expensive, technologically incompatible, or impossible to mobilize within the necessary timeframe.
Finally, disruption must be capable of spreading to other industrial segments, generating consequences disproportionate to the economic value of the component concerned.
This combination transforms industrial dominance into a potential capacity to obstruct production.
A company may be able to replace a supplier holding a substantial market share when several competitors possess comparable capabilities.
Substitution becomes considerably more difficult when the supplier controls proprietary technology, specialized facilities, refining processes, or industrial expertise requiring years to develop.
Strategic power therefore does not necessarily reside in ownership of the original resource.
It may be located much further along the value chain.
This is precisely what the rare earth industry demonstrates.
Rare Earths: Industrial Power Lies Beyond Extraction
Rare earths comprise seventeen chemical elements used in a wide range of industrial applications.
They are essential to certain electric motors, wind turbines, electronic equipment, optical systems, and defense technologies.
Despite their name, several of these elements are not exceptionally scarce in the Earth's crust.
The real difficulty lies in identifying economically viable deposits and mastering the complex processes required to transform ores into usable industrial materials.
Extraction represents only the first stage.
Ores must subsequently be processed, individual elements separated, metals refined, and materials transformed into components meeting precise technical specifications.
These activities are not geographically distributed in the same way.
Within the supply chain for neodymium-iron-boron permanent magnets, known as NdFeB magnets, estimates cited by the BIS attribute approximately 58% of the relevant raw material extraction to China.
Its dominance becomes considerably greater in subsequent stages.
China accounts for approximately 90% of separation, metal refining, and magnet manufacturing capacity.
These figures, drawn from earlier industry assessments and incorporated into the BIS analysis, illustrate a fundamental reality: the geography of mineral resources does not necessarily correspond to the geography of industrial power.
A country may possess substantial deposits without controlling the processes required to transform them into strategic components.
Conversely, a country importing some of its minerals may retain a dominant position by controlling processing capabilities.
This explains why opening new mines does not automatically guarantee industrial independence.
Even when extraction becomes geographically diversified, raw materials may continue to pass through the same refining centers.
Dependency is then relocated rather than eliminated.
China's position reflects decades of accumulated industrial capacity, investment, technical expertise, research, and economies of scale.
It cannot be rapidly replicated through political decisions alone.
Developing a mine, constructing a separation facility, mastering a metallurgical process, and qualifying a magnet for industrial applications are distinct operations.
Each requires specific investments, capabilities, and timelines.
Diversifying resources therefore does not automatically diversify value chains.
Japan: Reducing Dependency Without Eliminating It
Japan's experience illustrates both the possibilities and limitations of industrial diversification.
In 2010, tensions between Tokyo and Beijing exposed Japan's vulnerability to disruptions in Chinese rare earth supplies.
Japanese authorities subsequently launched a strategy to reduce this exposure.
It combined alternative sourcing, investment in new production capabilities, recycling initiatives, and technological improvements designed to reduce the consumption of certain materials.
The results were significant.
According to data cited in the BIS study, China's share of the value of Japanese rare earth imports declined from approximately 80% to a low near 40% in the mid-2010s.
This demonstrates that industrial dependency can be reduced when investment and technological policies are sustained over time.
But it also reveals the limitations of measuring diversification exclusively through aggregate trade flows.
A declining Chinese share of total imports does not mean that every category of material has become substitutable.
For certain products, including lanthanum oxide, Japanese dependence on Chinese suppliers remains almost complete in the data examined.
Diversification also carries costs.
Alternative supplies may be more expensive, less readily available, or exposed to different disruptions.
Japan's experience therefore demonstrates that a statistical reduction in dependency does not necessarily eliminate critical chokepoints.
An economy may become less dependent overall while remaining highly vulnerable in a small number of strategically important materials.
Resilience must consequently be assessed at the level of individual products, industrial processes, and applications.
Gallium: Limited Economic Value Can Conceal Major Strategic Importance
Gallium provides another example of the divergence between economic weight and industrial importance.
This metal, which is not classified as a rare earth element, is used in several advanced electronic technologies.
It is particularly important for compound semiconductors such as gallium arsenide and gallium nitride, which are employed in radio-frequency applications, optoelectronics, telecommunications, and defense systems.
Gallium production has a distinctive characteristic.
It is primarily recovered as a by-product of other industrial processes, particularly bauxite processing within the aluminum industry.
Its availability therefore partly depends on activities for which gallium is not the principal output.
According to 2025 data cited by the BIS, China accounted for approximately 99% of global low-purity primary gallium production.
Such concentration can create substantial difficulties for manufacturers or countries seeking alternative supplies.
Yet the macroeconomic consequences of a disruption are not necessarily proportional to this concentration.
The BIS researchers reference a simulation published by the US Geological Survey in 2024.
Under its central scenario, a complete one-year Chinese embargo on net gallium exports would reduce US gross domestic product by approximately $3.1 billion, equivalent to around 0.01%.
This is a modeled estimate, not an observed economic loss.
At the scale of the American economy, the impact appears relatively limited.
But aggregate figures can conceal much more serious consequences for specific activities.
A component representing a negligible share of an equipment system's total cost may nevertheless be indispensable to its operation.
Its absence may delay production, prevent the delivery of critical systems, or compromise particular technological capabilities.
The consequences can therefore be concentrated among a limited number of companies, industrial programs, or military applications without necessarily causing a major contraction in national GDP.
This distinction is essential.
Strategic vulnerability cannot be measured exclusively through the market value of trade or aggregate output losses.
It also depends on the criticality of applications, substitution possibilities, and the time required to rebuild capabilities.
An economically marginal material can therefore become strategically decisive.
Thailand, 2011: When a Chokepoint Can Be Overcome
The second case examined by the BIS presents a different configuration.
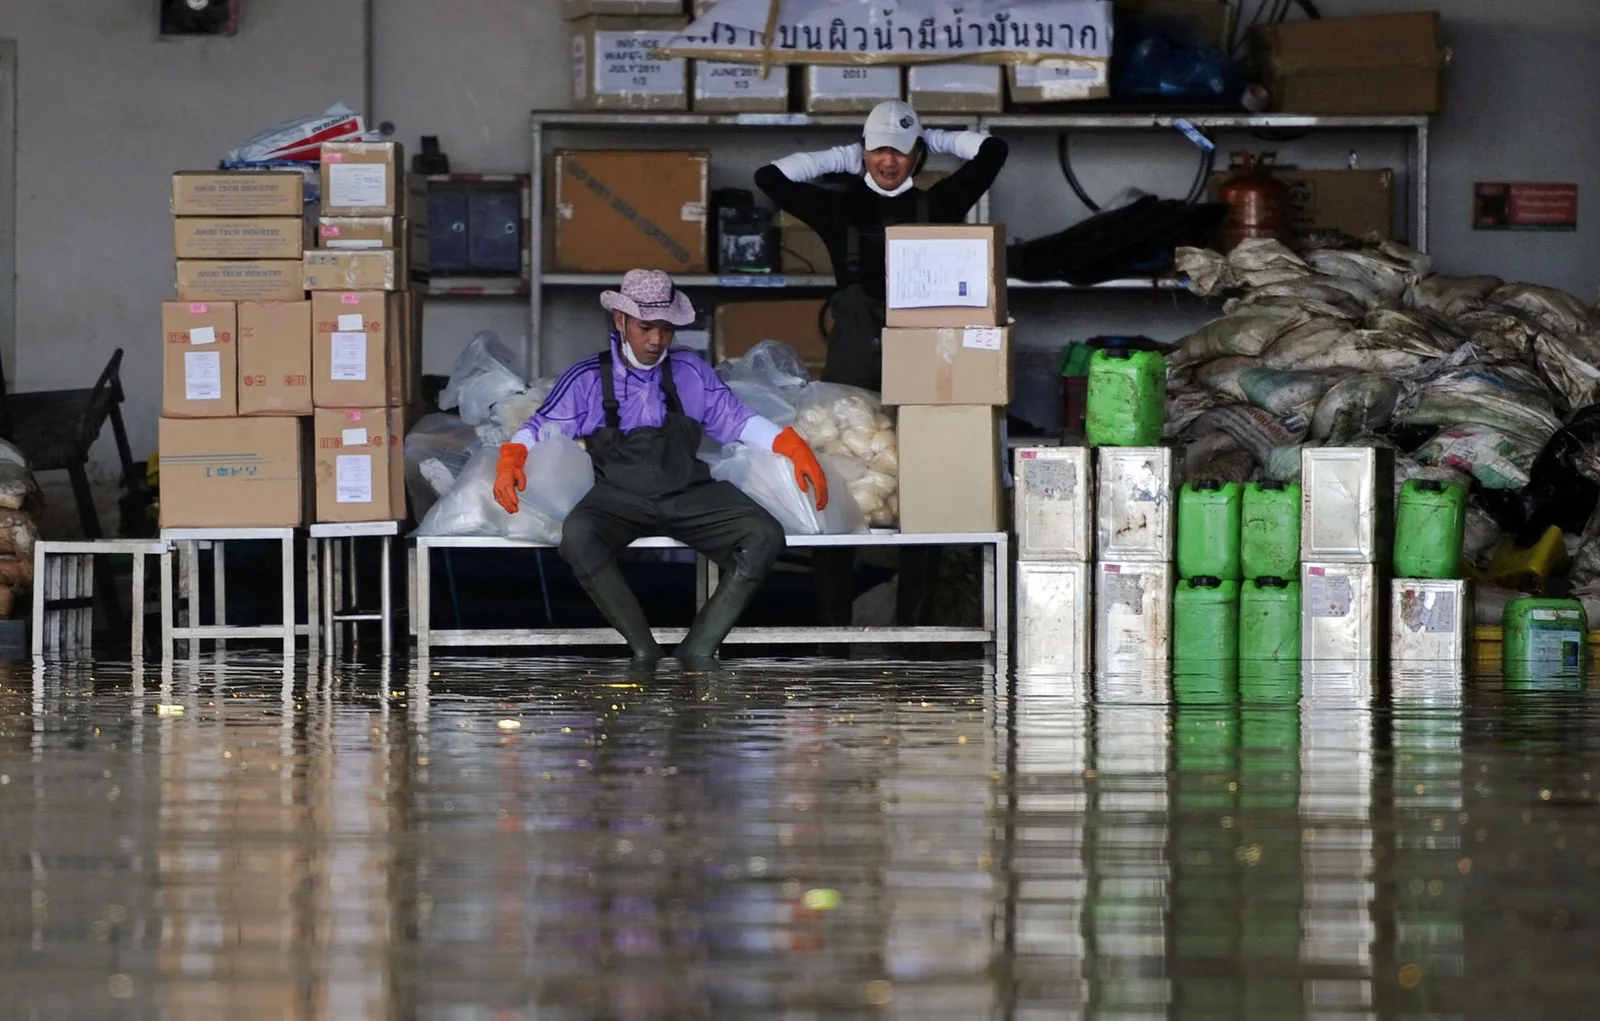
In 2011, severe flooding struck Thailand and disrupted several major industrial zones.
At the time, the country occupied a central position in global hard disk drive manufacturing.
It accounted for approximately 40% of worldwide production.
The floods caused a dramatic decline in industrial activity.
In the fourth quarter of 2011, Thai hard disk drive production fell by 55% compared with the same period a year earlier.
The consequences spread to computer equipment manufacturers and businesses dependent on these components.
Western Digital, one of the world's leading hard disk drive manufacturers, was particularly affected.
Its quarterly shipments declined from 52.2 million units in the fourth quarter of 2010 to 28.5 million units one year later.
The disruption was substantial.
Yet the underlying problem differed fundamentally from the rare earth dependency.
The floods did not eliminate the industrial knowledge required to manufacture hard disk drives.
They did not create a new technological monopoly.
Instead, they temporarily disabled existing facilities and disrupted supplier networks.
The capabilities still existed, even though restoring them required complex operations.
Western Digital was able to restart production within 46 days.
This did not represent a complete recovery of previous output levels, but it demonstrated the effectiveness of an organization capable of responding rapidly.
The company mobilized manufacturing capacity in Malaysia, relocated certain inventories to less exposed locations, and coordinated with suppliers to restore operations.
It also retained much of its workforce during the disruption.
Approximately 38,000 employees were kept on payroll at 75% of their regular wages, according to information cited in the study.
This decision facilitated recovery by preserving teams and industrial expertise.
Thailand's experience demonstrates that substantial geographical concentration does not necessarily constitute an irreversible structural dependency.
When technologies remain available, equipment can be repaired, and production can be transferred, resilience may depend primarily on crisis management rather than a complete restructuring of industrial geography.
Two Crises, Two Different Forms of Vulnerability
The comparison between rare earths and hard disk drives highlights two fundamental categories of risk.
The first involves structural dependencies.
These emerge when production capabilities, technological processes, or essential expertise are durably concentrated.
Reducing them generally requires new investment, alternative industrial capabilities, and sometimes changes in the technologies being used.
The second involves temporary disruptions.
These occur when existing activities are interrupted by external events such as natural disasters, industrial accidents, logistical failures, or temporary transportation restrictions.
In such situations, inventories, supplier redundancy, geographical flexibility, and business continuity arrangements can play decisive roles.
The distinction is not absolute.
An initially temporary disruption can become structural when damage permanently destroys facilities, causes suppliers to disappear, or leads to the loss of essential expertise.
Conversely, a structural dependency may be partially mitigated by inventories sufficient to support a transition period.
The duration of the shock is therefore a central variable.
Inventories covering several months may protect a company against a disruption lasting a few weeks.
They cannot necessarily resolve an industrial dependency that may persist for years.
Similarly, constructing an entirely new factory to protect against an exceptional short-term event may represent a disproportionate investment.
Resilience policies must therefore reflect the probability, duration, and consequences of the risks involved.
Semiconductors: Multiple Dependencies Embedded in a Single Industry
This analytical framework can be extended to other strategic industries.
Semiconductors provide a particularly revealing example.
Their value chain involves a succession of highly specialized activities: chip architecture, electronic design automation software, intellectual property, equipment manufacturing, wafer fabrication, materials processing, assembly, packaging, and testing.
Concentration does not occur at the same point across these activities.
Some segments depend on an extremely limited number of suppliers.
Others have production capabilities distributed across several regions.
A semiconductor manufacturer's vulnerability cannot therefore be assessed solely through the geographical location of its factories.
It also depends on access to manufacturing equipment, software, materials, and the expertise required to operate those facilities.
Building a new factory does not guarantee autonomy if the equipment needed to operate it remains manufactured elsewhere.
Similarly, mastering chip design is insufficient when a company lacks access to appropriate fabrication capabilities.
Technology restrictions can consequently disrupt industrial value chains without directly interrupting raw material supplies.
They may restrict access to equipment, slow the modernization of production facilities, or prevent the adoption of newer technological generations.
The actual chokepoint may therefore lie in a machine, a license, a manufacturing process, or a specialized capability.
This illustrates a major transformation in industrial power.
Strategic control increasingly depends not only on the ability to manufacture large volumes of products but also on controlling the technologies that enable others to manufacture them.
Artificial Intelligence: Concentration Is Shifting Toward Infrastructure
The development of artificial intelligence reinforces this logic.
Advanced AI systems depend on an exceptionally complex industrial infrastructure.
They require computing accelerators, specialized memory, networking equipment, data centers, electricity supplies, and cooling systems.
Each component belongs to a distinct value chain.
Certain activities are highly concentrated, particularly in the most advanced segments of semiconductor fabrication and packaging.
Others depend on local constraints, including electricity availability, grid connection capacity, and cooling infrastructure.
These dependencies do not generate identical risks.
An electricity interruption may be temporary when backup systems or alternative capacity are available.
A shortage of advanced components may persist much longer when additional manufacturing capacity requires years of investment.
Restrictions on access to specialized equipment may prevent infrastructure modernization for an extended period.
AI resilience must therefore be examined across several layers.
Owning a data center does not mean controlling the supply chain of the processors it uses.
Having access to electricity does not guarantee access to computing equipment.
Developing AI models does not ensure technological autonomy when training depends on computing infrastructure controlled by a small number of actors.
The expansion of artificial intelligence does not eliminate traditional industrial dependencies.
It creates new ones while increasing the strategic importance of physical infrastructure.
Industrial Sovereignty Does Not Necessarily Mean Producing Everything
Governments have increasingly introduced economic security policies in response to these vulnerabilities.
Trade restrictions, geopolitical tensions, and supply disruption risks have strengthened arguments in favor of reshoring.
But the BIS analysis suggests that a uniform response would be misguided.
Reconstructing entire national value chains can be extraordinarily expensive.
Economies of scale, specialization, and industrial concentration are also important sources of productivity.
Systematically eliminating them would mean sacrificing some of the economic advantages created by the international division of labor.
The objective should therefore not necessarily be to manufacture every component domestically.
It should be to identify dependencies whose interruption would generate unacceptable consequences and determine the most effective means of reducing them.
For some activities, supplier diversification may be sufficient.
For others, strategic inventories provide appropriate protection.
Where dependency results from an industrial process controlled almost exclusively by an external actor, developing alternative capabilities becomes more important.
In certain cases, the most effective solution may be technological.
Redesigning a product to reduce its consumption of a critical material can diminish dependency without replicating an entire production chain.
Such strategies nevertheless require the scientific and industrial capabilities needed to develop alternatives.
Economic sovereignty should therefore be understood less as complete self-sufficiency than as the capacity to preserve essential economic functions despite external disruptions.
Europe and the Challenge of Industrial Diversification
The European Union illustrates this search for balance.
Its Critical Raw Materials Act, adopted in 2024, establishes several benchmarks for 2030.
It aims to develop European extraction capacity equivalent to at least 10% of annual consumption of strategic raw materials, where domestic reserves permit.
It also establishes benchmarks of at least 40% for processing capacity and 25% for recycling capacity.
The regulation additionally seeks to prevent any single third country from supplying more than 65% of the EU's annual consumption of a strategic raw material at a relevant stage of processing.
These benchmarks do not mean that the European Union has already achieved the corresponding levels.
They are intended to guide investment and reduce excessive concentration.
Their implementation nevertheless presents a significant challenge.
Geographical diversification does not automatically produce diversification of industrial control.
A facility located in Europe may remain dependent on foreign equipment, licensed technologies, material suppliers, or companies controlling multiple stages of the value chain.
Similarly, new processing capacity is insufficient if its output does not meet the technical requirements of downstream manufacturers.
Industrial security therefore requires a deeper assessment than the territorial distribution of facilities.
It demands an understanding of the relationships between ownership, technology, financing, expertise, and market access.
Can Emerging Economies Transform Resources Into Industrial Power?
This challenge is equally relevant to emerging economies.
Many countries possess substantial mineral, energy, or agricultural resources without controlling the industrial stages that generate the greatest value.
They export raw materials and subsequently import components, equipment, or finished products.
Economic power is consequently concentrated in intermediate and downstream activities.
This configuration limits the industrial benefits derived from resource extraction.
It may also create new dependencies when extractive projects rely on technologies, financing, and infrastructure controlled entirely by foreign partners.
For these economies, industrial diversification represents an opportunity.
But not every processing activity offers the same strategic value.
Some require enormous production volumes to achieve competitiveness.
Others depend on complex processes, patents, or supplier networks that are difficult to reproduce.
The objective should not be to process every resource domestically regardless of cost.
Instead, countries should identify segments in which they can develop sustainable advantages, acquire transferable capabilities, and strengthen their position within global value chains.
This approach is particularly relevant for African economies pursuing industrialization strategies.
Resource ownership provides a starting point.
It does not guarantee technological mastery or the ability to negotiate a more advantageous position in the global industrial system.
The central challenge is to convert available resources into productive capabilities, expertise, and bargaining power.
How Can a Genuine Industrial Chokepoint Be Identified?
Assessing global value chains ultimately requires moving beyond traditional concentration indicators.
A supplier's market share remains important, but it is insufficient to measure vulnerability.
Strategic assessment must examine several complementary dimensions.
The first is component criticality.
Would the absence of a particular component actually prevent production of the final product, or could technical alternatives be used?
The second is substitutability.
Can another supplier be mobilized quickly? Do competing products meet the same standards? Would switching require additional certification?
The third concerns recovery timelines.
How long would it take to repair a facility, increase a competitor's output, or develop entirely new production capacity?
The fourth concerns industrial control.
Are supposedly independent suppliers owned by the same group? Do they rely on identical technologies or infrastructure?
The fifth concerns economic transmission.
Would a disruption affect a single product, an entire industry, or several interconnected sectors?
Finally, the sixth concerns strategic consequences.
Could the temporary loss of a component compromise critical infrastructure, military capabilities, or technologies that are difficult to replace?
The combination of these factors makes it possible to distinguish economically efficient concentration from systemic vulnerability.
This approach avoids two opposing mistakes.
The first is treating every foreign dependency as a threat requiring domestic production.
The second is assuming that sufficiently developed global markets will always provide alternative suppliers.
In some industries, markets can absorb disruptions.
In others, alternative capabilities simply do not exist at the required scale.
Economic Power Also Belongs to Those Who Can Prevent Others From Producing
The evolution of global value chains reveals a deeper transformation in the distribution of economic power.
For decades, industrial capabilities were primarily assessed through production volumes, exports, available resources, and market shares.
These indicators remain essential.
But they do not always identify the most strategically significant positions.
An actor can exercise considerable influence without accounting for a large share of an industry's total economic value.
Sometimes, controlling a single indispensable, difficult-to-replace stage is sufficient.
That position may result from mastery of a chemical process, industrial equipment, software, manufacturing technology, or physical infrastructure.
It may also reflect the accumulation of specialized expertise that competitors cannot rapidly reproduce.
In an economy organized around interconnected value chains, power therefore resides not only in the ability to produce.
It also resides in the capacity to make production possible for others.
And, under certain circumstances, in the ability to make that production impossible.
This does not necessarily mean that an actor controlling a chokepoint will seek to disrupt supplies.
It does mean that other participants must incorporate this possibility into their industrial and strategic decisions.
The distinction matters: dependency can create vulnerability even when no disruption occurs.
The underlying risk can influence investment decisions, commercial negotiations, technological choices, and public policy.
A New Geography of Global Resilience
The central contribution of the BIS study is to demonstrate that industrial responses must be proportionate to the nature of the vulnerabilities involved.
Thailand's floods revealed the importance of operational flexibility, workforce retention, and the ability to reorganize production rapidly.
Rare earths demonstrate that dependencies rooted in the long-term concentration of technologies and processing capabilities cannot be resolved through inventory management alone.
These two cases do not provide an exhaustive classification of every strategic supply chain.
They nevertheless offer a valuable framework for understanding contemporary industrial transformations.
As geopolitical tensions intensify, economic security can no longer be understood as a simple choice between globalization and reshoring.
It requires a precise understanding of interdependencies.
Governments must identify which activities are genuinely critical.
Companies must determine which suppliers could compromise their operations if temporarily or permanently unavailable.
Investors must distinguish industrial positions that can be readily challenged from those protected by substantial technological and operational barriers.
And emerging economies must identify the stages of global value chains in which they can develop genuinely strategic capabilities.
The decisive question is therefore not whether an economy depends on foreign suppliers.
In a global production system, virtually every economy is interconnected.
The real question is which dependencies can be overcome, at what cost, within what timeframe, and with what consequences.
Because the most dangerous industrial chokepoint is not necessarily where production is most concentrated. It is where, when supply is interrupted, no viable alternative can be mobilized in time.
Atlas Limits Research Desk
Atlas Limits’ editorial and analytical desk.