By preparing to list its Indian subsidiary through the sale of 86.42 million existing shares, Carlsberg is pursuing a transaction whose significance extends far beyond the brewing industry. No new capital will be injected into the company: the proceeds will go to selling shareholders. The structure illustrates a transformation in the role of India's financial markets. Long regarded primarily as a destination for international investment, India is increasingly becoming a marketplace where multinational corporations can realize the value of established businesses, reorganize ownership structures, and unlock capital without necessarily surrendering operational control.
An Initial Public Offering That Will Not Raise Capital for the Company
On October 27, 2026, Carlsberg India published updated documents relating to its proposed initial public offering.
The transaction involves the sale of 86.42 million existing shares, according to information reported by Reuters on October 28.
This feature represents the central financial characteristic of the operation.
Unlike a conventional initial public offering involving the issuance of new shares, the proposed transaction consists exclusively of an offer for sale, or OFS.
The securities offered to investors will therefore come from the holdings of existing shareholders.
Carlsberg India itself will receive no direct proceeds from the transaction.
The company will not raise new equity capital to finance expansion, reduce debt, or strengthen its cash position.
Instead, the transaction will allow selling shareholders to convert part of their ownership in an unlisted company into liquid financial assets.
It is therefore an ownership monetization transaction rather than a capital increase.
This distinction is essential to understanding its strategic significance.
An initial public offering can provide a company with new resources to finance growth.
It can also allow existing owners to realize part of the value accumulated through years of investment.
In Carlsberg India's case, the second objective dominates the proposed structure.
The publication of updated offering documents represents an important regulatory milestone, but the listing has not yet taken place.
The final offering price, definitive valuation, subscription timetable, and listing date remain to be confirmed.
The announcement should therefore not be interpreted as a completed IPO.
From Industrial Investment to Financial Value Realization
Carlsberg's proposed transaction reflects a broader transformation in how multinational corporations manage their international investments.
When a foreign company enters an emerging market, it generally commits capital across several categories.
It finances industrial facilities, establishes distribution networks, develops brands, recruits employees, and adapts products to local conditions.
These investments are undertaken in anticipation of future revenues and profits.
Historically, their value remained largely embedded within the valuation of the multinational parent company.
International investors could benefit indirectly from the growth of foreign subsidiaries by owning shares in the parent.
However, this arrangement did not necessarily ensure that each local business received a distinct market valuation reflecting its individual prospects.
Listing a subsidiary changes that relationship.
It creates a dedicated market for the subsidiary's shares.
It allows investors to assess its financial performance, growth opportunities, and risks directly.
It can also reveal a market valuation different from the value implicitly assigned to the business within the international group.
For the parent company, such a transaction can offer several potential advantages.
It may allow shareholders to realize part of the value of historical investments.
It may preserve exposure to the subsidiary's future growth.
It can also establish an observable market valuation for an asset that was previously privately held.
An IPO can therefore transform a long-term industrial investment into a partially liquid financial asset.
The strategic objective is no longer simply to build a successful business abroad, but also to determine when and under what conditions the value created can be realized.
India: From an Investment Destination to a Market for Capital Monetization
The strategic implications extend beyond Carlsberg.
India has occupied an increasingly important position in the international strategies of major corporations for several decades.
Its population, expanding infrastructure, evolving consumer markets, and industrial development have attracted substantial foreign investment.
Multinational companies have progressively accumulated significant industrial, commercial, and technological assets.
Some of these businesses have now reached a scale that allows them to access public capital markets independently.
This evolution creates a new phase in the international investment cycle.
During the first phase, foreign companies invest to establish commercial and industrial operations.
During the second, their local businesses reach a scale capable of generating meaningful revenues and profits.
During the third, existing owners may seek to realize part of the value of their holdings.
An initial public offering represents one possible mechanism for this third phase.
India's stock market therefore serves not only as a destination for investment capital.
It also provides a platform through which historical shareholders can transfer ownership to new investors.
This transformation could strengthen India's role in global capital management strategies.
It does not necessarily mean that multinational corporations are withdrawing from the country.
A minority divestment can allow a group to maintain its industrial presence while recovering part of the financial resources committed to its subsidiary.
The critical distinction is between reducing an ownership stake and abandoning an operating business.
These decisions can have very different economic consequences.
Hyundai, LG, and Carlsberg: Three Examples of a Shared Financial Logic
Carlsberg's proposed listing follows a pattern already illustrated by other international corporations.
Hyundai Motor listed its Indian subsidiary in October 2024 through an offering structured around the sale of existing shares.
The transaction allowed the South Korean group to monetize part of its ownership in an industrial business developed over several decades.
The Indian subsidiary did not receive the proceeds directly.
The parent company nevertheless retained majority ownership.
The transaction therefore separated the realization of financial value from the retention of industrial control.
LG Electronics adopted a comparable approach when its Indian subsidiary entered the stock market in 2025.
The offering involved the sale of existing shares, allowing the South Korean group to realize part of the value of its Indian operations.
These transactions differed in sector, valuation, and ownership structure.
Nevertheless, they illustrate a common mechanism.
Multinational corporations that have built substantial businesses in India are using local equity markets to introduce new shareholders into their ownership structures.
This approach can preserve industrial operations while reorganizing financial ownership.
Carlsberg is now preparing a comparable transaction in the brewing industry.
The succession of these offerings suggests that Indian capital markets are becoming an increasingly relevant instrument of international asset management for companies operating across different sectors.
However, it would be misleading to conclude that every multinational pursuing such a transaction intends to reduce its strategic commitment to India.
Corporate motivations can vary.
Some groups may wish to finance investments elsewhere.
Others may seek greater financial flexibility.
Still others may believe that a local listing will provide a more accurate valuation of their subsidiary.
In each case, the stock market becomes an instrument for reorganizing capital.
Carlsberg India: Nearly Two Decades of Industrial Development
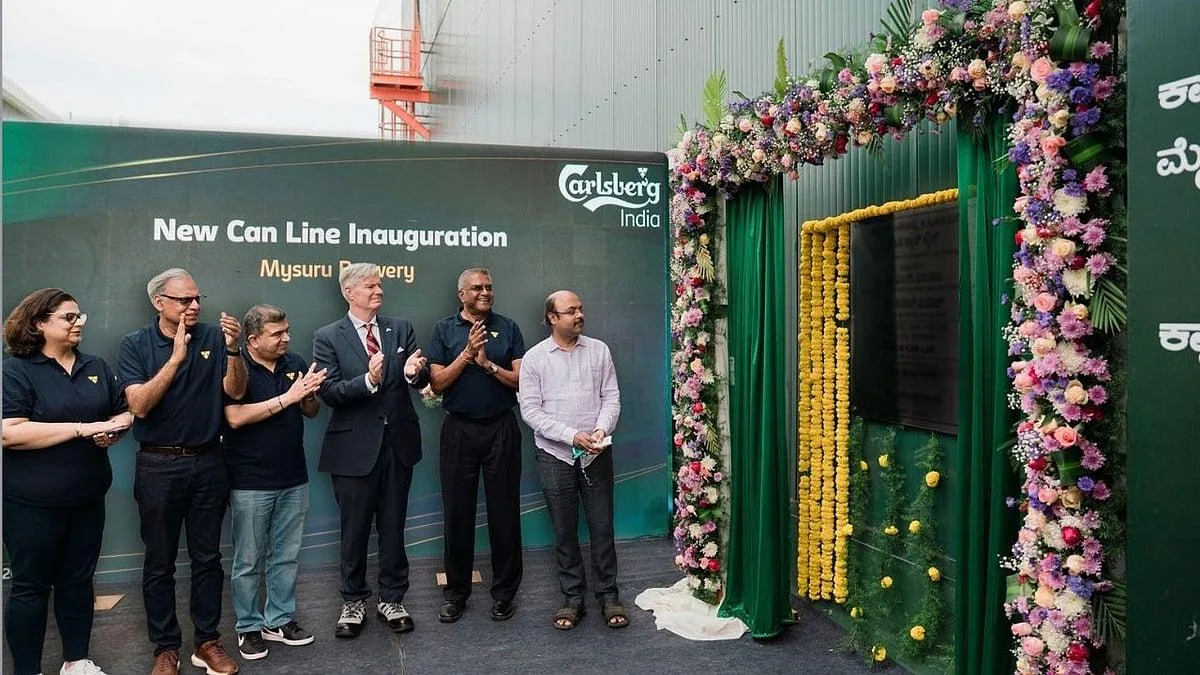
The value Carlsberg is seeking to bring to public markets rests on an industrial presence established almost two decades ago.
The Danish group began operating in India in 2007.
Since then, it has developed a portfolio of brands, production facilities, and distribution networks across significant parts of the country.
Carlsberg India operates seven breweries directly.
The updated offering documents also refer to nine third-party manufacturing facilities.
This structure combines company-controlled industrial capacity with external production arrangements.
It allows the business to expand its commercial presence while limiting the need to own every production facility.
The company markets brands including Carlsberg and Tuborg, alongside products adapted to the preferences of Indian consumers.
Its commercial strategy combines internationally recognized brands with offerings positioned across different segments of the market.
The ability to adapt products to local conditions is an important competitive factor.
India's alcoholic beverage market is characterized by regulatory, fiscal, and commercial differences between states.
Distribution and sales are subject to rules that vary considerably across the country.
Companies must therefore operate within a fragmented regulatory environment.
This fragmentation creates operational constraints, but it can also favor businesses with established local expertise and extensive industrial networks.
A Significant Market Position That Requires Careful Interpretation
According to information presented in connection with the proposed IPO, Carlsberg India claims a market share of 21.9% across sixteen important Indian states and union territories.
This figure must be understood within its specific geographic scope.
It should not automatically be interpreted as an equivalent share of the entire Indian market.
Separate information relating to the 2026 financial year indicated a nationwide market share of approximately 16.2%, compared with 14.6% in the previous year.
These figures are not directly interchangeable.
They may reflect different geographic coverage or measurement methodologies.
The distinction matters for investors.
A company can hold a particularly strong position in selected regions while recording a lower national market share.
In a country as geographically extensive and regulatorily fragmented as India, the distribution of sales can have important implications for profitability.
Regional markets differ in taxation, distribution rules, and competitive conditions.
Growth in sales volumes therefore does not necessarily produce equivalent financial results across all territories.
The quality of growth depends on its composition as well as its pace.
Strong Revenue Growth Does Not Automatically Produce Higher Profits
Recent financial figures present a mixed picture.
For the quarter ended June 2026, Carlsberg India reported a 21.5% increase in net revenue to 13.66 billion rupees.
Profit, however, declined by 3.9% to 1.58 billion rupees.
These figures highlight a divergence between commercial growth and earnings performance.
Revenue increased substantially.
Profit declined slightly.
Based on the reported quarterly figures, profit represented approximately 11.6% of net revenue.
This ratio should not automatically be interpreted as an operating margin, since reported profit and net revenue do not necessarily correspond to the accounting measures used to calculate EBIT or EBITDA.
Nevertheless, it provides a useful indication of the relationship between commercial activity and final earnings.
Annual figures offer a different perspective.
For the financial year ended March 2026, Carlsberg India reported operating revenue of approximately 87.09 billion rupees, representing a decline of 2.2%.
Profit increased by approximately 22% to 5.35 billion rupees.
These developments demonstrate that the company's financial performance can vary significantly depending on the reporting period and indicator considered.
They also underline the importance of examining earnings quality rather than focusing exclusively on sales growth.
For investors considering participation in the IPO, several questions will be important.
How much of the company's growth comes from higher volumes?
How much reflects changes in prices or product mix?
To what extent do commercial and promotional expenses affect margins?
Are recent financial performances representative of a sustainable trajectory?
These questions will play a central role in determining the valuation investors are willing to assign to Carlsberg India.
Valuation: The Central Question Behind the IPO
The number of shares proposed for sale is now documented.
However, this figure alone does not establish the value of the transaction.
The final valuation will depend on the price at which the shares are offered.
Gross proceeds will correspond to the number of shares sold multiplied by the offering price.
The implied equity market capitalization will depend on that price and the total number of shares outstanding.
Three financial concepts must therefore be distinguished.
The IPO transaction value represents the value of the shares sold.
Market capitalization represents the theoretical market value of all outstanding shares.
Enterprise value incorporates the adjustments required to move from equity value to the value of the operating business, including net financial debt under the relevant valuation methodology.
These measures are not equivalent.
A company can conduct a relatively limited minority offering while achieving a substantial market capitalization.
Conversely, an offering involving a large number of shares does not necessarily imply a high valuation if the offering price is modest.
Earlier market estimates suggested that the proposed transaction could potentially raise approximately $700 million.
That figure should be treated as a preliminary market indication rather than the definitive value of the offering.
Without a confirmed final price, a precise valuation would be premature.
Carlsberg India's ability to secure an attractive valuation will depend on several factors.
Investors will examine volume growth, margins, returns on invested capital, capital expenditure requirements, and the outlook for the Indian market.
They will also compare the business with listed companies operating in the beverage and consumer goods sectors.
The valuation will therefore depend less on the international recognition of Carlsberg's brands than on the subsidiary's capacity to generate sustainable future cash flows.
Industrial Control Can Survive Financial Dilution
One of the most important strategic dimensions of the proposed transaction concerns the distinction between economic ownership and corporate control.
An IPO does not necessarily mean that a parent company relinquishes control of its subsidiary.
A multinational can sell a minority stake while retaining a majority of voting rights.
It may also preserve influence through board representation, contractual arrangements, and industrial relationships.
In Carlsberg India's case, the final ownership structure will need to be assessed once the offering terms are confirmed.
The exact percentage of equity transferred to public investors will depend on the total number of shares outstanding and the definitive transaction structure.
It would therefore be premature to present a precise post-listing ownership distribution.
The underlying financial principle remains clear.
A minority divestment can allow a multinational to recover capital without surrendering operational control.
This possibility represents one of the principal attractions of subsidiary IPOs.
It allows corporations to partially separate two objectives that were previously closely connected: retaining a strategic asset and realizing the financial value it represents.
The parent company can remain exposed to future earnings while reducing the proportion of its capital tied up in an unlisted business.
However, this strategy also creates new obligations.
The arrival of public minority shareholders increases requirements relating to transparency, governance, and investor protection.
Corporate decisions must take account of the interests of all shareholders within the applicable legal framework.
Financial and commercial relationships with the parent company may also attract greater scrutiny.
A public listing therefore changes not only ownership but also governance requirements.
India's Growing Role in Global Capital Management
The Carlsberg transaction reveals an evolution in the role of Indian financial markets within multinational corporate strategies.
Traditionally, foreign direct investment involves transferring capital into an economy to develop productive activities.
Listing a subsidiary creates a different financial movement.
Domestic or international investors acquire ownership interests in an established business.
Historical shareholders receive the proceeds of the sale.
Depending on the ownership structure, those proceeds may subsequently be deployed into other activities, retained at the parent-company level, or allocated to different financial objectives.
This does not necessarily constitute an economic withdrawal.
The local business may continue operating, maintaining its facilities, and expanding sales.
But ownership of part of the business changes hands.
This transformation is particularly important in economies where financial markets have developed sufficient depth to absorb large transactions.
A market's capacity to finance new businesses represents one indicator of financial maturity.
Its ability to provide liquidity to historical investors represents another.
India is increasingly developing both functions.
It attracts capital intended to finance growing companies.
It also provides opportunities for international corporations to realize part of the value of their previous investments.
This dual function can strengthen India's importance in global capital allocation decisions.
Competition to Attract Major Public Listings
The attractiveness of Indian capital markets rests on several factors.
The first is the size of the investor base.
The expansion of financial savings, investment funds, and retail participation contributes to potential demand for listed equities.
The second concerns the growth prospects of certain domestic businesses.
Investors may accept relatively high valuations when they anticipate sustained increases in revenue and earnings.
The third concerns visibility.
A publicly traded company benefits from an observable market valuation that can be monitored continuously.
The fourth concerns liquidity.
Shareholders may, subject to regulatory restrictions and market conditions, have more opportunities to sell their holdings than in a wholly private company.
These advantages are not guaranteed.
An IPO may encounter insufficient investor demand.
The proposed valuation may be considered excessive.
Market conditions may deteriorate between the publication of offering documents and the opening of subscriptions.
Volatility may also affect share performance after listing.
For multinational corporations, timing is therefore critical.
A company may possess strong industrial assets without achieving the valuation expected by its owners if investors become more cautious.
The success of an offering depends on the alignment between sellers' expectations and new shareholders' required returns.
The Regulatory Complexity of India's Beer Market
India's brewing industry presents characteristics that complicate financial analysis.
Alcohol regulation is largely determined at the state level.
Rules governing licenses, distribution, taxation, and pricing can therefore vary considerably across the country.
This fragmentation affects industrial strategies.
Companies must adapt their commercial organizations to local conditions.
They may also encounter different restrictions across regional markets.
Taxation is another important factor.
Taxes and duties on alcoholic beverages can represent a substantial proportion of final consumer prices.
Changes in fiscal policy can therefore directly influence demand, margins, and distribution decisions.
The industry is also exposed to the costs of raw materials, packaging, transportation, and energy.
These costs can evolve independently of sales volumes.
The ability of producers to pass increases on to consumers depends on regulatory conditions and competitive intensity.
Commercial expenditure also plays an important role in brand development.
Higher sales volumes may require substantial promotional investment.
Such expenditure can support growth while temporarily weighing on margins.
For investors, Carlsberg India's value will depend on its ability to manage several constraints simultaneously: commercial expansion, regional regulation, industrial costs, and profitability.
Market size alone does not guarantee financial performance.
The Risks of an Entirely Secondary IPO
The proposed transaction structure offers advantages to selling shareholders, but it also requires a particular interpretation by prospective investors.
In an IPO involving newly issued shares, the proceeds can contribute directly to financing future corporate growth.
Investors can then assess the projects that will be funded with the new resources.
In an entirely secondary offering, the financial logic is different.
The funds paid by subscribers go to existing shareholders.
They do not directly strengthen the company's financial resources.
Future growth must therefore be financed through existing resources, operating cash flows, debt, or subsequent financing transactions.
This characteristic does not make the IPO inherently less legitimate.
It changes the nature of the investment being offered.
New shareholders are purchasing an ownership interest in an existing business whose future prospects they must evaluate.
They are not directly financing a new expansion program through the offering.
This distinction can influence their assessment of the proposed price.
A high valuation must be justified by expected future earnings and the quality of existing assets.
The reputation of the parent company or the general dynamism of the Indian economy will not be sufficient.
The Ownership Question: Why Sell Part of a Growing Business?
A fundamental question accompanies this type of transaction.
Why would a multinational corporation sell part of a subsidiary operating in a market that still offers development opportunities?
Several economic explanations are possible.
The first concerns capital diversification.
A group may wish to reduce the concentration of financial resources in particular assets or geographic markets.
The second concerns investment allocation.
Capital recovered from a divestment can be directed toward activities that management believes offer more attractive prospective returns.
The third concerns valuation.
When financial markets assign a favorable value to a subsidiary, a partial sale can allow existing owners to realize part of that value.
The fourth concerns financial flexibility.
Converting an unlisted ownership stake into cash can improve a group's capacity to finance other projects, reduce debt, or reorganize its portfolio.
The fifth concerns financial transparency.
Listing a subsidiary provides an observable market valuation and makes its performance more directly comparable with listed competitors.
These motivations should not all be automatically attributed to Carlsberg.
They represent the principal economic considerations that may explain this category of transaction.
The actual use of sale proceeds will depend on decisions taken by the selling shareholders.
The IPO should therefore be understood as a capital-management operation whose precise ownership and financial consequences will be determined by its final structure.
A Changing Relationship Between International Capital and Emerging Markets
The developments observed in India form part of a broader transformation in international financial relationships.
Emerging markets have traditionally been analyzed primarily as destinations for capital originating in developed economies.
European, American, Japanese, and South Korean companies invested in these markets to reach new consumers, reduce certain production costs, or diversify industrial operations.
That logic remains important.
However, some emerging economies now possess financial markets capable of directly valuing the assets built by international investors.
Capital flows are becoming more complex.
Multinational corporations continue to invest in productive businesses.
At the same time, they can use local markets to reorganize ownership of those businesses.
Domestic investors can acquire stakes in companies previously held entirely by foreign groups.
This development can contribute to the expansion of national capital markets.
It can also gradually change the distribution of economic ownership.
However, it does not necessarily imply the localization of strategic control.
A listed subsidiary may remain majority-owned by its foreign parent.
Essential industrial decisions may continue to depend on the multinational group's global strategy.
Three dimensions must therefore be distinguished: the location of operations, ownership of capital, and exercise of control.
These dimensions can evolve independently.
Carlsberg India's proposed IPO illustrates precisely this separation.
The Implications for Carlsberg and Its Shareholders
For the Danish group, the proposed listing could create a new financial configuration.
Part of the value of its Indian subsidiary would become directly observable through public markets.
The sale of shares could allow selling shareholders to recover financial resources.
The subsidiary would gain a broader shareholder base.
The listing could also increase its visibility among Indian and international institutional investors.
At the same time, it could strengthen transparency requirements concerning financial results, investments, and relationships with other companies within the group.
The IPO could therefore change how the performance of the Indian business is evaluated.
However, it would not automatically improve profitability.
Operational value creation would continue to depend on revenue growth, cost management, investment quality, and regulatory risk.
A financial transaction can modify a company's ownership structure.
It cannot replace the economic conditions required for sustainable development.
This distinction is fundamental to understanding the limits of an asset monetization strategy.
What the Carlsberg India Transaction Really Reveals
The proposed IPO can be understood at three levels.
At the company level, it represents a liquidity transaction allowing existing shareholders to sell part of their holdings.
At the multinational level, it offers a potential instrument for reorganizing ownership and allocating capital.
At the national level, it illustrates the development of an Indian financial market capable of accommodating significant listings involving subsidiaries of international corporations.
These dimensions are interconnected.
The depth of India's capital markets makes monetization possible.
Monetization can allow multinational corporations to reorganize financial resources.
That reorganization may subsequently influence future investment decisions.
The transaction therefore highlights an evolution in the economic function of public offerings.
IPOs do not exist exclusively to finance companies seeking expansion.
They can also serve as mechanisms for transforming ownership and facilitating the international circulation of capital.
This function becomes particularly important in economies where multinational corporations have accumulated substantial assets over several decades.
Conclusion — India Is Becoming a Market for Realizing Corporate Value
Carlsberg India's proposed initial public offering is more than a financial transaction in the brewing industry.
It reflects a deeper evolution in multinational ownership strategies and the role of Indian capital markets.
By proposing the sale of 86.42 million existing shares without issuing new securities, the transaction is structured to allow selling shareholders to realize part of the value of their holdings.
The company itself will receive no direct proceeds from the offering.
That distinction is essential.
It demonstrates that financial markets are not merely instruments for financing corporate growth.
They can also transform long-term industrial investments into liquid, tradable assets with publicly observable valuations.
The precedents established by Hyundai Motor and LG Electronics illustrate the broader relevance of this strategy.
For multinational corporations, India is increasingly becoming a market where companies can not only build valuable businesses but also realize part of their financial value.
The success of Carlsberg India's proposed listing will nevertheless depend on its pricing, investor demand, and the subsidiary's economic prospects.
Recent financial data reveal a business with a significant industrial presence, but also one exposed to profitability pressures and the regulatory complexities of its sector.
An IPO will not eliminate these constraints.
It will change how they are assessed and distributed among shareholders.
The strategic implications ultimately extend beyond Carlsberg. As India's capital markets deepen, multinational corporations gain another instrument for balancing ownership, control, and financial value realization.
India is no longer simply a destination where international capital arrives to invest. It is increasingly becoming a marketplace where that capital can be valued, partially sold, and redeployed. In this transformation, a country's financial power is measured not only by its ability to attract investment, but also by its capacity to provide liquidity and facilitate the circulation of capital.
Atlas Limits Research Desk
Atlas Limits’ editorial and analytical desk.