As China prepares for its November 11 shopping festival, artificial intelligence is entering the machinery of mass consumption. Usage credits, token packages and subscriptions to AI assistants are joining the products offered on e-commerce platforms. Behind this development lies a deeper transformation: after data and digital services, access to artificial intelligence is becoming a commodity distributed directly to consumers.
For decades, computing power was primarily purchased in the form of machines, software or services designed for businesses. The rise of cloud computing gradually transformed that relationship, allowing organizations to rent remote computing resources according to their needs and consumption volumes. Generative artificial intelligence is extending this evolution, but it could also introduce a new dimension: turning access to AI models into an ordinary commercial product, marketed directly to individuals.
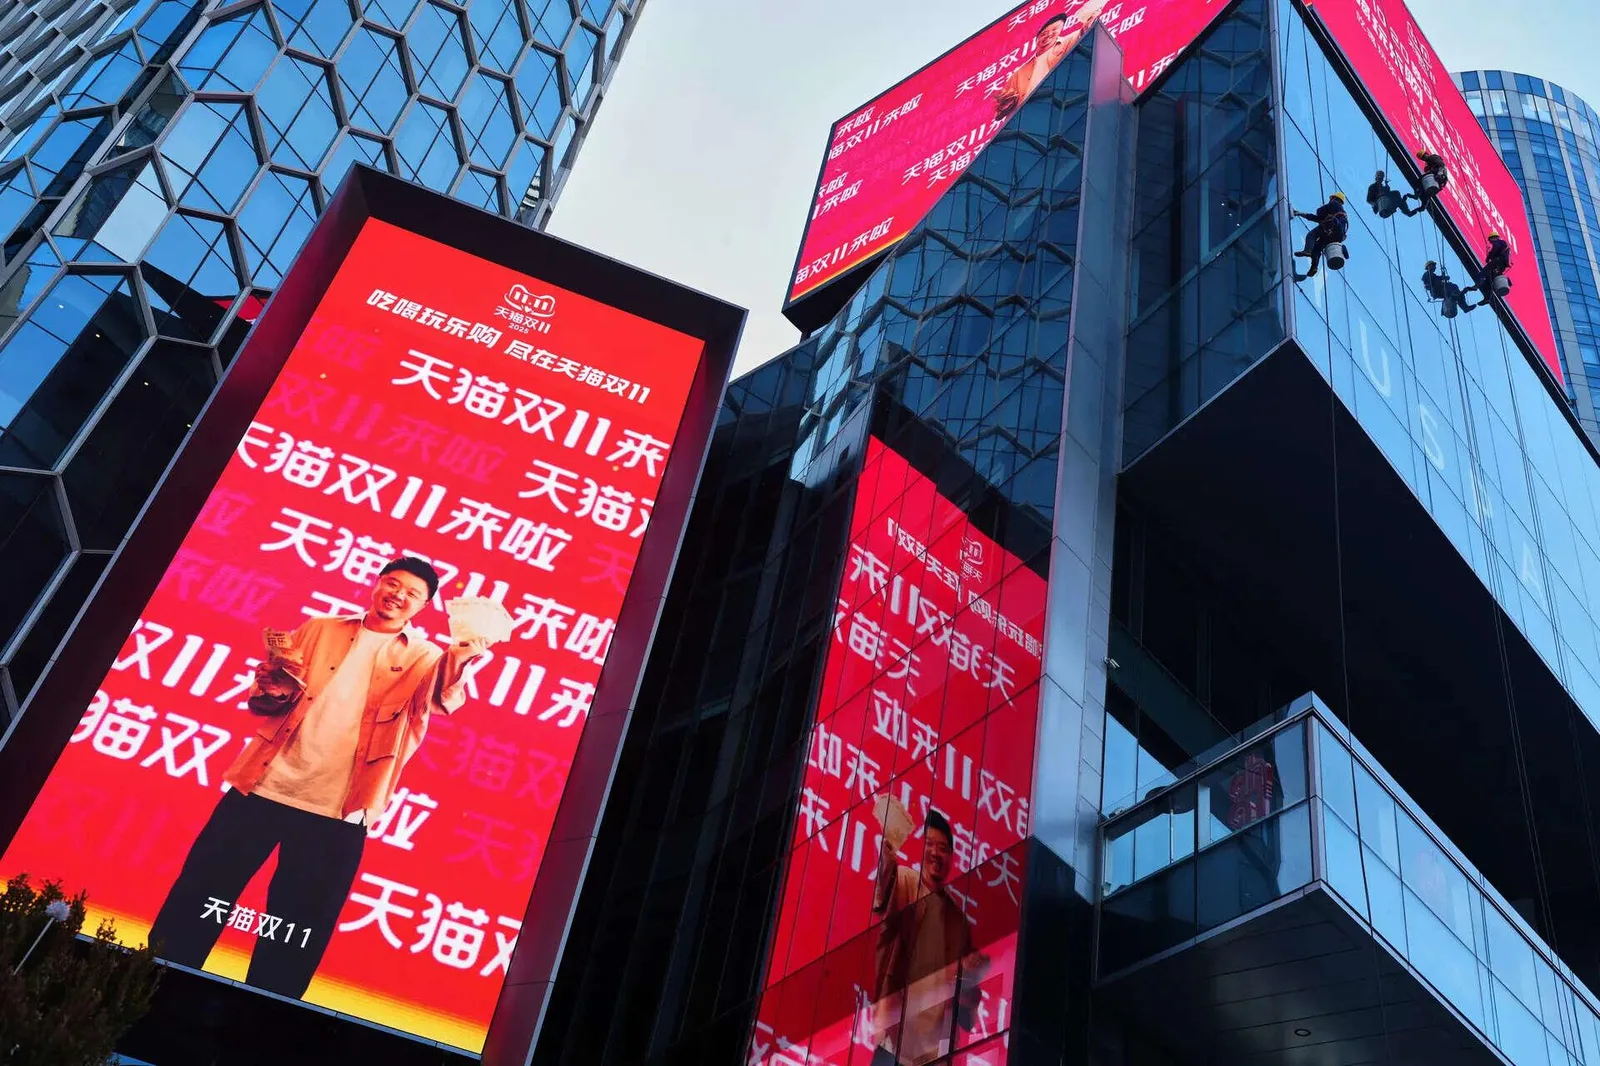
In China, the November 11, 2026 shopping campaign, known as Double 11 or Singles’ Day, offers an illustration of this transformation. On major e-commerce platforms, AI usage packages are appearing alongside electronic devices, digital subscriptions and consumer services.
The phenomenon remains at an early stage, but it reveals an important shift. Artificial intelligence is no longer presented exclusively as a technology embedded in applications or as infrastructure reserved for businesses. It is also beginning to be marketed through prepaid, measurable usage rights distributed through conventional digital retail channels.
This development raises a question extending far beyond the Chinese market: after learning to sell data, storage and subscriptions, is the digital economy preparing to commercialize artificial intelligence as a new unit of everyday consumption?
November 11: A Laboratory for Digital Consumption
Singles’ Day occupies a distinctive position in China’s economy. Originally associated with an informal celebration of being single, November 11 became one of the country’s largest commercial events through the expansion of major e-commerce platforms.
Over time, the campaign has moved far beyond its original format as a single day of promotions. It now extends over several weeks and mobilizes a vast network of manufacturers, retailers, digital platforms, payment providers, logistics companies and technology suppliers.
This exceptional concentration of supply and demand also makes it a testing ground for commercial innovation. Companies can experiment with new products, distribution methods and consumer behavior.
The 2026 edition introduces a particularly revealing category: packages and credits providing access to artificial intelligence services.
According to information reported by Reuters on November 3, offers linked to AI model usage were marketed during the promotional activities preceding November 11. A livestream shopping event hosted on November 2 by Li Jiaqi, a prominent figure in Chinese digital commerce, helped introduce these products to an audience extending well beyond developers and technology professionals.
Sales figures communicated around certain promotional operations suggest significant initial interest. They must nevertheless be interpreted cautiously: purchases made during a promotional campaign are not sufficient evidence of sustained demand.
The more important development lies elsewhere. Services previously sold through specialized technical environments are now being presented, promoted and distributed using the ordinary mechanisms of e-commerce.
The technology is changing its distribution channels before its economic model has fully stabilized.
From Computing Power to Consumer Credits
Understanding this evolution requires distinguishing several realities often grouped under the general concept of computing power.
The first concerns physical computing resources: processors, specialized accelerators, memory, storage and data center capacity. These infrastructures form the material foundation on which artificial intelligence systems operate.
The second involves access to models that have already been trained. When users interact with a conversational assistant, request a translation or generate a document, they rely on a remote computing system that performs a sequence of operations to produce a response.
The third concerns the commercial unit used to measure and charge for that access. In language models, this unit frequently takes the form of a token, an element of text processed by the system.
Tokens, however, are not a universal measure of computing power. Their cost depends on several factors, including the model being used, the length of the input, the volume of generated output and the resources required for processing.
One million tokens consumed by a lightweight model therefore do not necessarily represent the same cost as one million tokens processed by a more complex system.
Packages sold to individual consumers should not be confused with the acquisition of dedicated computing capacity. In most arrangements of this kind, buyers obtain usage rights governed by contractual conditions, consumption limits and sometimes expiration dates.
This distinction is fundamental.
What becomes a consumer product is not necessarily computing power itself, but commercial access to processing capacity supplied by an operator.
The evolution resembles the telecommunications industry. Consumers do not directly purchase mobile network infrastructure; they buy packages allowing them to use communication capacity.
Artificial intelligence could gradually adopt a comparable commercial structure, although its billing units remain considerably less standardized.
China and the Industrialization of AI Usage
The emergence of these offers comes amid intense competition among Chinese companies developing artificial intelligence models, cloud infrastructure and digital platforms.
The Chinese market has several characteristics that make it particularly suitable for this experiment.
First, it possesses a highly developed e-commerce ecosystem capable of rapidly distributing new services to an enormous consumer population. Its platforms combine product discovery, recommendation systems, payments, promotions and customer loyalty mechanisms.
This integration reduces the barriers to distributing digital services that, in other markets, still require separate purchasing processes.
China also has a substantial ecosystem of companies developing artificial intelligence models, including Alibaba, Baidu, Tencent, ByteDance and several specialized providers.
These companies do not all pursue identical strategies. Some prioritize integrating artificial intelligence into existing services, while others seek to develop technical platforms accessible to businesses and software developers.
The commercialization of consumer packages nevertheless introduces an additional possibility: transforming part of this technological competition into direct competition over usage volumes, prices and access conditions.
This dynamic could accelerate the adoption of artificial intelligence beyond professional users.
It could also reinforce the position of platforms that already maintain commercial relationships with hundreds of millions of consumers.
Under these conditions, distribution becomes almost as important as technical performance.
A provider may develop a particularly effective model without possessing the channels required to commercialize it at scale. Conversely, a platform with an enormous audience can accelerate adoption by incorporating a service into its promotional mechanisms.
The competition surrounding artificial intelligence is therefore no longer limited to model development. It increasingly concerns access to the market.
The Price of Intelligence
Commercializing AI credits raises a central economic question: how should a service be priced when its technical costs evolve rapidly and its quality varies considerably across models?
In traditional digital services, consumption units are relatively straightforward to identify. Storage is measured in gigabytes, communications in minutes or data volumes, and subscriptions provide access to defined functionalities.
Artificial intelligence introduces an additional difficulty.
Two responses generated by different models may have substantially different costs, even when they appear similar to the user. Producing a simple text, analyzing a lengthy document, generating an image and executing complex reasoning tasks require different levels of computing resources.
Providers must therefore balance several objectives: offering attractive prices, covering infrastructure costs, maintaining service quality and financing the investments required to develop new models.
Selling prepaid credits can help address some of these objectives.
It allows providers to collect revenue before the service is consumed, simplify the purchasing experience and encourage users to explore functionalities they might not otherwise have accessed through a technical billing environment.
It also creates opportunities for promotional packages based on volumes, bonuses or expiration periods.
But this commercial model has limitations.
Unused credits may expire. Attractive pricing may apply only to particular models or periods. Available performance may vary across packages, while consumers rarely possess enough information to compare the actual cost of processing.
The result could be a pricing environment that appears abundant but remains difficult to interpret.
Artificial intelligence may become commercially more accessible without immediately becoming economically more transparent.
A New Economy of Usage
The most significant transformation may concern the structure of the market itself.
Until now, much of the artificial intelligence economy has been organized around three categories: companies developing models, those supplying the infrastructure required to operate them, and those integrating these technologies into applications.
Direct sales of credits introduce another layer: usage distributors.
These intermediaries could play an increasingly important role in the relationship between model providers and consumers.
They could combine multiple services, offer packages, organize promotions, process payments and direct users toward particular technologies rather than others.
This development could open the way to commercial strategies already observed in telecommunications, cloud services and entertainment platforms.
Credits could be bundled with subscriptions, incorporated into loyalty programs or offered alongside other digital products.
Over time, distributors might seek to differentiate their offerings not only through pricing, but also through the quality of available models, processing speeds, permitted volumes and accessible functionalities.
This is not yet a standardized market. Commercial offers remain heterogeneous, and usage rights are not necessarily transferable between providers.
Nevertheless, the underlying economic logic is beginning to emerge.
A complex technological resource can be transformed into a simplified commercial product, distributed by companies that do not necessarily control the entire underlying infrastructure.
Apparent Abundance and Physical Scarcity
One of the contradictions of this evolution lies in the relationship between commercial abundance and physical constraints.
For consumers, a token package may create the impression of an almost unlimited digital resource. Advertised volumes can be substantial, promotional prices low and access immediate.
For providers, however, every interaction relies on physical infrastructure.
Data centers require substantial investment, specialized equipment, communication networks, cooling systems and continuous electricity supplies.
Declining unit costs for certain processing tasks do not eliminate these constraints. They may even contribute to increasing total demand as users multiply their interactions.
This relationship between efficiency and consumption represents one of the fundamental challenges of the artificial intelligence economy.
If services become sufficiently accessible to be used daily by hundreds of millions of people, processing volumes could increase considerably.
Providers would then face a dual requirement: reducing unit costs while expanding their overall capacity.
The commercial success of artificial intelligence could therefore intensify pressure on the physical infrastructure that makes it possible.
The energy question, often discussed in relation to large data centers and industrial investment, would acquire an additional dimension through the everyday consumption of individuals.
Behind every digital package would remain a material chain involving electricity generation, transmission and consumption.
Artificial intelligence would be sold as an intangible service, but its development would remain deeply dependent on physical resources.
Competition Moves Toward the Consumer
This evolution could also reshape the strategies of major technology companies.
During the early stages of generative artificial intelligence, competition focused heavily on model performance, computing capacity and access to specialized components.
These dimensions remain essential. But the expansion of AI into everyday activities introduces another form of competition: the ability to transform an available technology into a consumption habit.
The objective is no longer simply to persuade businesses to integrate models into their information systems.
It increasingly involves convincing individuals to use these services regularly and subsequently pay to maintain or expand their consumption.
Chinese platforms possess a structural advantage in this respect: they already control many of the commercial mechanisms required to convert user attention into transactions.
Livestream shopping, personalized recommendations, temporary promotions and integrated payment systems can all contribute to accelerating this transition.
But the shift from occasional purchases to recurring consumption remains uncertain.
A consumer may purchase a package during a promotional campaign without subsequently developing sufficiently frequent usage to justify renewal.
The true measure of success will therefore not be limited to the number of packages sold during Double 11.
It will depend on activation rates, actual consumption volumes, renewal frequency and providers’ ability to retain users after promotional campaigns end.
These indicators will help distinguish a temporary commercial phenomenon from the formation of a durable market.
Toward a New Global Unit of Consumption?
The Chinese experiment could signal a broader evolution without necessarily determining the future structure of the global market.
In many countries, consumers already access artificial intelligence through monthly subscriptions, limited free versions or functionalities integrated into existing software.
Prepaid credits introduce another approach: allowing users to purchase a defined volume of usage without necessarily committing to a permanent subscription.
This model could appeal to occasional users, students, independent professionals and consumers seeking greater control over their digital expenditure.
It could also facilitate the commercialization of specialized services whose usage requirements vary considerably between individuals.
However, international expansion would require addressing several difficulties.
The first concerns transparency. Consumers would need to understand what they are purchasing and be able to compare usage conditions.
The second concerns portability. Credits tied to a particular provider do not constitute a universal unit of consumption.
The third involves consumer protection, particularly the transparency of contractual conditions, credit expiration periods and the handling of personal data.
Finally, service quality will remain decisive. Cheaper artificial intelligence is not necessarily more useful if its performance fails to meet users’ needs.
The future of this market will therefore depend as much on trust and quality as on advertised prices.
From Technology to an Ordinary Product
The history of the digital economy suggests that major technological transformations often become fully visible when they cease to appear exceptional.
Internet access, remote storage, mobile communications and digital services gradually moved beyond specialized environments to become part of everyday life.
Artificial intelligence could follow a comparable trajectory, but with one distinctive characteristic: what is being commercialized is not simply access to information or infrastructure, but the ability to delegate certain intellectual operations to automated systems.
This distinction does not mean that human intelligence becomes a commodity interchangeable with computing power. Rather, it indicates that certain functions previously performed directly by users can now be offered as measurable and billable services.
China’s November 11 shopping campaign is therefore revealing.
It demonstrates how a technology still associated with industrial investment, research laboratories and major corporations can be presented as a product accessible to ordinary consumers.
The phenomenon remains too recent to conclude that a standardized global market for artificial intelligence credits is emerging. The commercial offers observed also provide insufficient evidence to assess their profitability or the future loyalty of buyers.
Nevertheless, they indicate an important shift.
Following the competition to build increasingly powerful models, another competition is developing around their distribution, pricing and integration into everyday activities.
Companies controlling this commercial relationship could acquire considerable influence over how artificial intelligence is consumed.
China is now experimenting with this transformation through the familiar mechanisms of e-commerce.
Behind the promotions, packages and token volumes, a much larger industrial question is beginning to take shape: when artificial intelligence becomes an ordinary consumer product, where will value ultimately concentrate — in the models themselves, in the infrastructure operating them, or in the platforms selling access?
The answer will help determine the economic organization of artificial intelligence in the years ahead.
Main Sources
Reuters — November 3, 2026. Reporting on the commercialization of artificial intelligence tokens and usage packages during China's Singles’ Day shopping campaign, including livestream sales operations.
Xinhua — November 1, 2026. Reporting on emerging commercial offers and the integration of artificial intelligence services into Chinese promotional campaigns.
Alibaba Group — November 2026. Corporate communications concerning the 2026 Double 11 campaign and commercial initiatives involving artificial intelligence.
Technical documentation from AI model providers. Reference materials explaining token-based billing, API usage conditions and the distinction between model access and dedicated computing resources.
Atlas Limits Analysis — November 3, 2026.
Atlas Limits Research Desk
Atlas Limits’ editorial and analytical desk.