Artificial intelligence is already helping sustain the global economy through the scale of investment it generates. Yet behind the promises of productivity and economic growth, a less visible transformation is emerging: the gradual automation of the tasks through which young graduates have traditionally entered professional life. The risk is not simply that jobs will disappear. It is that the mechanisms through which skills are developed, careers are built, and prosperity is passed from one generation to the next may be fundamentally altered.
In Bangkok, where the International Monetary Fund and the World Bank are holding their Annual Meetings, a contradiction is beginning to emerge in the outlook for the global economy. While energy pressures, trade uncertainty, and financial imbalances continue to weigh on economic activity, investment in artificial intelligence is helping sustain a growth trajectory that international institutions might otherwise have considered more vulnerable.
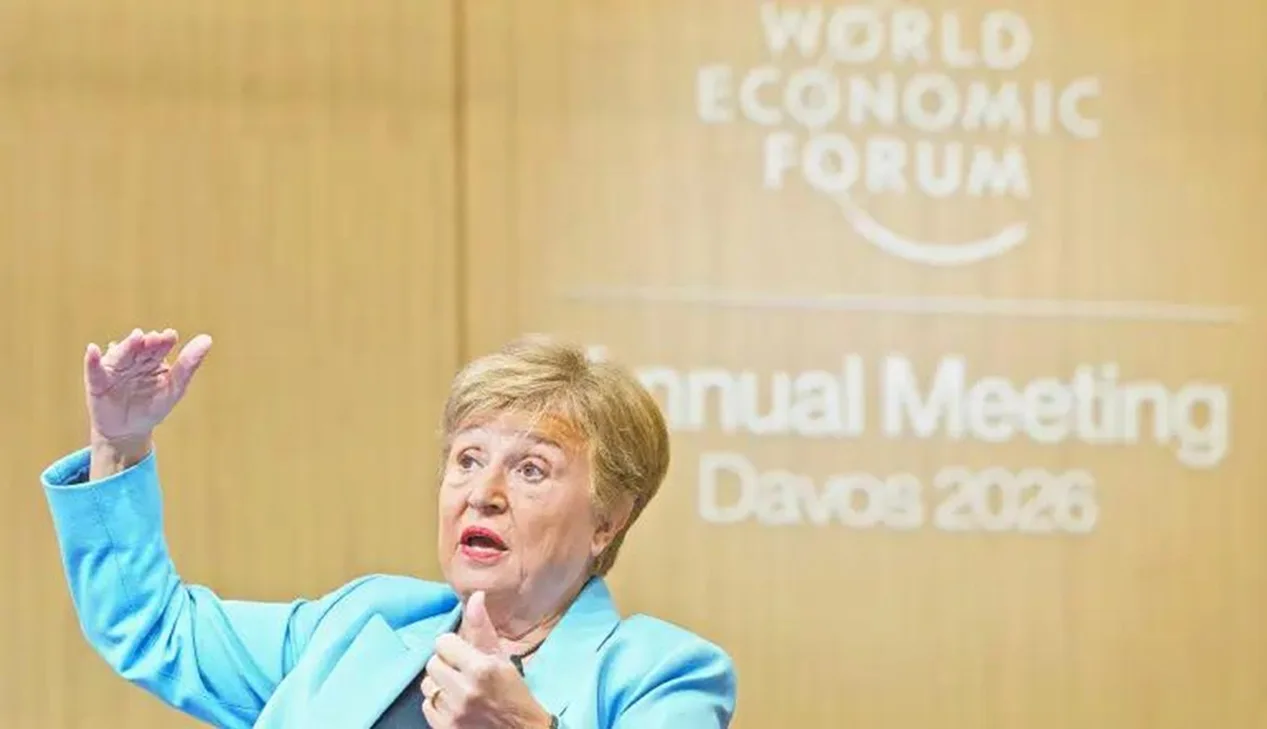
IMF Managing Director Kristalina Georgieva has highlighted the increasingly significant role of spending on digital infrastructure. Data centers, semiconductors, electricity networks, computing equipment, and processing capacity have become major sources of investment across the international economy.
According to estimates presented by the Fund, artificial intelligence could contribute an additional 0.5 to 1 percentage point to growth in Asia's advanced economies and between 0.2 and 0.8 percentage points in emerging Asian economies. These figures describe potential economic effects whose time horizons and underlying assumptions must be distinguished from the immediately observable contribution of investment spending.
But another concern has entered the discussions. Singapore's President, Tharman Shanmugaratnam, has drawn attention to the employment prospects of young graduates, whose initial opportunities to enter the workforce could be affected by automation.
The question extends far beyond Asian labor markets. It touches one of the fundamental mechanisms of modern economies: the ability of a newly educated generation to enter junior positions, acquire experience, and gradually progress toward greater responsibilities.
Artificial intelligence could therefore help increase the wealth produced by an economy while making it more difficult for younger generations to access the first stages of its creation.
Growth Driven by Investment Before Productivity
The economics of artificial intelligence have an important distinguishing feature: its effects on investment are already visible, while its lasting consequences for productivity remain considerably harder to measure.
Building a data center immediately mobilizes capital, construction companies, electrical equipment manufacturers, semiconductor producers, and energy suppliers. The resulting expenditure supports economic activity before the installed systems have generated the efficiency gains expected from them.
This sequence helps explain part of the resilience of global growth.
Investment by major technology companies spreads across several industrial sectors. Chip manufacturers benefit from substantial orders, electricity producers anticipate rising demand, and companies specializing in cooling systems, networks, and power equipment find new markets.
The expansion of AI therefore operates as a large-scale industrial investment program, financed primarily by private companies with considerable financial resources.
But investment is not productivity.
A company can spend billions of dollars building computing infrastructure without the future economic benefits necessarily matching the capital committed. Profitability will depend on the actual utilization of installed capacity, service prices, customer demand, and the ability of businesses to transform their operating processes.
This distinction is essential to understanding the global outlook.
Infrastructure spending supports economic growth in the short term. Productivity gains, if they materialize, can support potential growth over a longer horizon. Between these two developments lies a period of uncertainty during which investment has already been committed, but its ultimate economic benefits remain unproven.
Economic history offers several comparable precedents. Electrification, computerization, and the development of the internet required considerable investment before their effects on productive organization became fully apparent.
New technologies do not transform every business immediately. They require organizational changes, new skills, and sometimes a complete restructuring of working methods.
Artificial intelligence may follow a similar trajectory, with one important difference: it intervenes directly in intellectual activities that have traditionally constituted an essential part of skilled employment.
Asia at the Center of a New Industrial Geography
The immediate benefits of this investment wave are not evenly distributed.
Economies with advanced electronics industries occupy a privileged position in the artificial intelligence value chain.
Taiwan plays a central role in manufacturing the most advanced semiconductors. South Korea possesses major industrial capabilities in computer memory, demand for which is increasing with the development of AI accelerators. Japan retains important positions in materials, production equipment, and several specialized components.
Singapore benefits from its role in digital infrastructure, technology services, and the regional organization of investment.
This industrial concentration helps explain why advanced Asian economies could derive particularly significant benefits from the expansion of AI.
The situation among emerging economies is more varied.
Some possess an industrial base capable of participating in electronics manufacturing, server assembly, or infrastructure construction. Others remain primarily users of technologies developed abroad.
The distinction is becoming increasingly important.
A country that manufactures the components required for artificial intelligence benefits directly from rising global investment. A country that imports this equipment must wait for its use to improve business productivity sufficiently to offset the expenditure involved.
This difference could reinforce existing economic imbalances.
The United States concentrates a significant share of the companies designing AI models, commercializing services, and financing infrastructure. Several Asian economies manufacture the essential hardware components. Other regions must find their place in a value chain whose most profitable segments may remain relatively concentrated.
Artificial intelligence does not therefore eliminate industrial dependencies. It may create new ones.
For economies that control neither the underlying technologies nor the infrastructure required to operate them, the challenge is to ensure that productivity gains achieved domestically are not absorbed by the cost of imported equipment and services.
The Entry-Level Employment Paradox
The transformation of labor markets is probably the most delicate dimension of this development.
The IMF estimates that approximately 40% of jobs worldwide are exposed to artificial intelligence, with higher proportions in advanced economies. Exposure does not mean that the jobs concerned will disappear. It indicates that some of their tasks may be modified, complemented, or replaced by automated systems.
The distinction is fundamental.
A financial analyst can use AI to examine documents more quickly. A lawyer can automate part of the research process. An engineer can accelerate certain programming operations. A consultant can produce preliminary analyses with less manual work.
In these situations, technology can increase employee productivity without necessarily replacing workers.
But this transformation presents a particular difficulty when it affects junior positions.
In many professions, the first years of a career involve relatively repetitive tasks: preparing spreadsheets, reviewing documents, gathering information, drafting summaries, testing software, or producing basic analyses.
These activities may appear secondary from the perspective of immediate productivity. Yet they perform an essential economic function.
They allow new employees to learn professional methods, understand organizational expectations, identify mistakes, and gradually develop the judgment required for more advanced responsibilities.
Automating these tasks can therefore produce a paradoxical outcome.
A company may become more efficient by assigning part of its junior employees' work to artificial intelligence systems. But if it simultaneously reduces recruitment, it risks weakening the process through which its workforce renews its expertise.
The problem may not become apparent immediately.
Experienced employees continue performing their functions. Productivity improvements may strengthen financial results. Personnel costs rise more slowly.
Several years later, however, the organization may discover that it lacks sufficient professionals with the intermediate experience necessary to replace senior managers and specialists.
The economy would then have automated part of its apprenticeship process without organizing an alternative means of transmitting expertise.
A Potential Breakdown in Skills Development
Professional training traditionally follows a gradual progression.
Knowledge acquired through education provides a theoretical foundation. Experience subsequently transforms that knowledge into operational competence.
This transformation requires time, mistakes, corrections, and progressive exposure to increasingly complex situations.
In intellectual professions, elementary tasks often perform a function comparable to apprenticeships in technical occupations.
A junior auditor learns to understand financial statements by participating in their verification. A lawyer develops legal reasoning by examining cases. A software engineer acquires an understanding of systems by writing, correcting, and testing code.
When these operations are automated, companies may be tempted to retain only positions requiring advanced expertise.
But expertise does not emerge spontaneously.
It would nevertheless be excessive to conclude that artificial intelligence will necessarily make young graduates less employable.
AI can also reduce barriers to learning. A beginner equipped with powerful tools may perform tasks previously reserved for more experienced professionals. They may gain faster access to technical knowledge, experiment more extensively, and develop new capabilities.
The effects will therefore depend on how work is organized.
A company that uses AI to support new employees may accelerate their training. A company that uses it primarily to eliminate entry-level functions may instead weaken its ability to develop future expertise.
The same technology can thus produce opposite consequences depending on management decisions.
This distinction changes the nature of the debate.
The question is no longer simply how many jobs artificial intelligence might replace, but how organizations will adapt their systems of training, recruitment, and professional advancement.
Education systems will also be affected.
If companies increasingly demand operational skills from the moment of recruitment, universities and training institutions will need to bring their teaching closer to real professional situations.
But this development has its limits. University education cannot entirely replace experience acquired within an organization.
Companies will therefore need to continue assuming part of the responsibility for training future employees, even when automation makes that investment appear less immediately necessary.
Productivity, Wages, and the Distribution of Value
The distributional consequences of artificial intelligence represent another major source of uncertainty.
An increase in productivity theoretically makes it possible to produce more with a given quantity of labor and capital.
But it does not automatically determine how the additional income will be distributed.
The gains may benefit consumers through lower prices, employees through higher wages, companies through improved margins, or capital owners through increased profits.
The outcome depends on competition, labor market institutions, the availability of skills, and the bargaining power of different economic actors.
Artificial intelligence could intensify certain asymmetries.
Companies controlling infrastructure, models, or platforms possess assets that are difficult to replicate. Employees capable of using these technologies to perform complex tasks may experience increases in productivity and professional value.
Conversely, workers whose functions become easily automatable could face pressure on wages or employment prospects.
This divergence will not necessarily follow traditional divisions between skilled and unskilled employment.
Some highly educated professions involve a substantial proportion of standardized cognitive tasks. Other activities, often less socially valued, require physical presence, adaptation to unpredictable environments, or human interactions that remain difficult to automate.
Educational qualifications alone are therefore no longer a sufficient indicator of technological exposure.
This development could change wage structures within individual professions.
Experienced employees capable of supervising automated systems, interpreting their results, and assuming responsibility for decisions may retain favorable positions.
New entrants, whose traditional tasks are partly automatable, could encounter greater difficulty accessing comparable career trajectories.
The risk would then be a widening gap between professional generations, independently of their initial educational attainment.
This outcome is not inevitable. Broad access to AI tools, effective competition, and appropriate training policies could also enable a more balanced distribution of gains.
But productivity growth does not guarantee that redistribution will occur.
Service Economies Facing a New Form of Competition
The international consequences could be particularly important for countries that have built their development strategies around service exports.
For several decades, globalization has allowed numerous emerging economies to participate in international value chains without necessarily possessing a manufacturing base comparable to those of major industrial powers.
Information technology services, call centers, data processing, accounting functions, and outsourced administrative activities have created skilled employment across several regions.
India and the Philippines illustrate two important, though distinct, trajectories of this transformation.
Artificial intelligence could alter the economic foundations of these activities.
A company that previously outsourced certain operations to benefit from lower labor costs can now consider partially automating them.
The economic calculation changes when the cost of a service depends less on the number of employees involved and more on the computing capacity available.
This does not mean that outsourced service industries will disappear. Companies operating in these sectors can themselves integrate AI, develop new services, and improve their competitiveness.
But advantages based primarily on differences in labor costs may become less significant.
The countries concerned will therefore need to move toward activities requiring greater judgment, specialization, and responsibility.
This transition could prove difficult if the functions most accessible to young graduates are precisely those experiencing the earliest transformations.
The issue then becomes macroeconomic.
An economy may educate an increasing number of graduates without creating enough positions in which their qualifications can be productively employed.
The gap between educational investment and professional opportunities could consequently widen.
For countries where the working-age population continues to expand rapidly, this prospect deserves particular attention.
The Risk of Concentrated Growth
The expansion of artificial intelligence could also alter the relationship between economic growth and employment.
Traditional phases of industrial expansion generally mobilize additional workers, either directly in production or indirectly through associated services.
Investment in AI infrastructure also creates jobs in construction, engineering, energy, and industrial equipment.
But once installed, some infrastructure can generate considerable economic activity with relatively limited staffing compared with the capital invested.
Data centers provide an illustration.
Their construction mobilizes numerous occupations. Their permanent operation subsequently relies on specialized teams but does not necessarily require a workforce proportional to the value of the equipment they contain.
This characteristic increases the capital intensity of the emerging digital economy.
A growing share of economic expansion may come from massive investment in technological assets whose direct operation requires relatively few workers.
Indirect employment and new activities enabled by these infrastructures may offset part of this development. Their ultimate scale, however, remains uncertain.
The net effect will depend in particular on whether companies use productivity gains to develop new products, reduce prices, and create new markets.
Economic history shows that technological transformations can generate professions that previously did not exist.
But it also demonstrates that transitions can be prolonged and that their benefits are not distributed evenly among workers, regions, and generations.
The real risk does not therefore necessarily lie in a permanent reduction in the total number of jobs.
It lies in the possibility of growth whose benefits become concentrated faster than new professional opportunities can spread throughout the economy.
A Question of Economic Policy
Governments have several instruments available to influence this trajectory, but none can guarantee a balanced transition on its own.
Education represents a first area of intervention. Training systems will need to integrate artificial intelligence tools without abandoning the fundamental skills required to understand, verify, and critically assess their outputs.
Training professionals to use a system is not the same as training them to evaluate its limitations.
The distinction will be particularly important in activities where errors can have legal, financial, medical, or industrial consequences.
Employment policies will also need to account for changing recruitment patterns.
Apprenticeships, professional internships, and company-based training programs could acquire renewed importance if traditional entry-level positions become less common.
Governments should nevertheless avoid permanently subsidizing jobs that businesses no longer need.
The objective should be to preserve the mechanisms through which experience is acquired rather than artificially maintaining every task that becomes automatable.
Competition policy will also matter.
Excessive concentration of AI infrastructure and services could limit the diffusion of productivity gains, reinforce dominant market positions, and increase the share of economic value captured by a small number of companies.
Conversely, broader access to technology could enable small and medium-sized enterprises to improve efficiency and develop new activities.
Taxation and social protection systems may eventually face more complex choices if capital income grows persistently faster than labor income.
These questions do not necessarily require introducing a specific tax on artificial intelligence. Rather, they invite governments to examine how existing systems distribute the costs and benefits of an increasingly capital-intensive economy.
The difficulty lies in supporting innovation without obstructing the economic adjustments it makes possible.
The Real Test of Global Growth
The IMF's assessment comes at a time when the global economy is searching for new engines of expansion.
Trade tensions are weakening international exchanges, fiscal constraints are limiting the room for maneuver available to many governments, and investment needs in energy and infrastructure remain substantial.
In this environment, artificial intelligence represents a potentially important source of growth.
It mobilizes private capital, supports several strategic industries, and creates opportunities to improve productivity across a wide range of activities.
But macroeconomic indicators alone will not establish whether this transformation represents broadly shared economic progress.
An increase in gross domestic product can coexist with stagnant wages in certain professions. Improved corporate margins can accompany reduced recruitment. Productivity can rise even as young graduates encounter greater difficulty securing their first qualified position.
These developments are not necessarily contradictory from an accounting perspective.
They may nevertheless be contradictory from a social perspective.
The challenge is to distinguish wealth creation from its diffusion throughout the economy.
Measuring the real effects of artificial intelligence will therefore require looking beyond investment expenditure, stock market valuations, and announced productivity improvements.
Changes in entry-level recruitment, the wage trajectories of young graduates, the time required to secure a first skilled position, and opportunities for professional advancement will become particularly important indicators.
It will also be necessary to determine whether companies automating elementary tasks continue training the specialists they will need in the future.
The answer will not depend exclusively on the technical capabilities of artificial intelligence models. It will depend on the economic and organizational choices made around their deployment.
Prosperity Still Needs a Next Generation
Artificial intelligence could become one of the most significant productive transformations of the coming decades.
It can reduce costs, accelerate research, improve industrial processes, and enable companies to produce more with limited resources.
It would be premature to conclude that this will result in widespread job destruction. Previous technologies have profoundly transformed professions without eliminating the need for human labor.
But it would be equally imprudent to assume that traditional mechanisms of adaptation will function automatically.
What distinguishes artificial intelligence is, in part, its ability to intervene in the intellectual tasks that have traditionally served as the first stages of many skilled careers.
The economy could therefore encounter a new difficulty: retaining experienced professionals while reducing the opportunities through which their successors acquire expertise.
This risk may not translate into an immediate employment crisis. It could emerge gradually in recruitment statistics, wage differences between generations, and difficulties renewing organizational capabilities.
Current investment can support global growth. Future productivity gains can increase the wealth available over the long term. But between these two developments lies a question that economic forecasts cannot resolve.
A society does not transmit prosperity solely through wealth, education, or income. It also transmits prosperity through the opportunities it gives each generation to learn a profession, assume responsibilities, and establish a place within the economy.
If artificial intelligence eventually allows companies to operate with fewer entry-level employees, they will still need to find a way to train their future experts. Otherwise, the economy may discover that what it gained in efficiency, it lost in its ability to prepare the next generation.
Main Sources
International Monetary Fund (IMF) — Gen-AI: Artificial Intelligence and the Future of Work, January 2024. Analysis of occupational exposure to artificial intelligence, potential productivity effects, and inequality risks.
International Monetary Fund (IMF) — World Economic Outlook Update, July 2026. Global growth projections and the macroeconomic environment.
International Monetary Fund and World Bank — 2026 Annual Meetings, Bangkok, October 2026. Statements by Kristalina Georgieva concerning AI-related investment and the economic outlook for Asia.
Reuters — October 12, 2026. Reporting on the IMF's assessment of AI investment as a contributor to global growth and discussions concerning employment opportunities for young graduates.
International Labour Organization (ILO) — Generative AI and Jobs: A Refined Global Index of Occupational Exposure, 2025. Analysis of occupational exposure to generative AI and the distinction between task transformation and job displacement.
Organisation for Economic Co-operation and Development (OECD) — OECD Employment Outlook 2023: Artificial Intelligence and the Labour Market. Analysis of the implications of artificial intelligence for employment, skills, wages, and work organization.
Atlas Limits Research Desk
Atlas Limits’ editorial and analytical desk.