The global manufacturing industry may be changing one of its oldest rules: producing goods no longer necessarily requires owning the factories. Sometimes, it is enough to know where those factories are, what they can manufacture, at what cost, and within what timeframe. The real challenge is turning that knowledge into completed orders, compliant products, and ultimately profits.
In India, Zetwerk is attempting to build a business around precisely this function. Founded in 2018, the company has expanded into a market traditionally occupied by specialized manufacturers, industrial traders, and subcontracting intermediaries. It offers customers an integrated approach to manufacturing, from identifying suppliers to quality control, logistics coordination, and delivery.
Its planned initial public offering in October 2026 represents an important stage in that development. According to information released on October 12, the transaction aims to raise approximately $518 million, at a targeted valuation of $2.64 billion. The subscription period is scheduled for October 15–19, with an initial listing expected on October 23.
These details remain subject to the final offering documents and market conditions. But the significance of the transaction already extends beyond the success of the capital raising itself.
Zetwerk is seeking financial recognition for an industrial model in which value comes not exclusively from owning production equipment, but from the ability to organize a manufacturing network large, reliable, and flexible enough to meet the requirements of major international customers.
Behind this ambition lies a broader question: in a global economy seeking to diversify its supply chains, who will control the manufacturing of industrial products tomorrow?
Industrial Fragmentation Becomes a Business
Industrial subcontracting is nothing new. For decades, large companies have distributed production among specialized suppliers, contract manufacturers, and subsidiaries operating across different countries.
The automotive, electronics, aerospace, and energy equipment industries already rely on complex structures in which a substantial share of value is often produced outside the facilities owned by the principal contractor.
But this organization comes at a cost.
Identifying a manufacturer capable of meeting technical specifications, verifying production capacity, negotiating prices, securing raw materials, monitoring component quality, and arranging deliveries require considerable resources. As value chains become more fragmented, coordination costs can become just as important as direct manufacturing costs.
This challenge is particularly visible in emerging industrial markets.
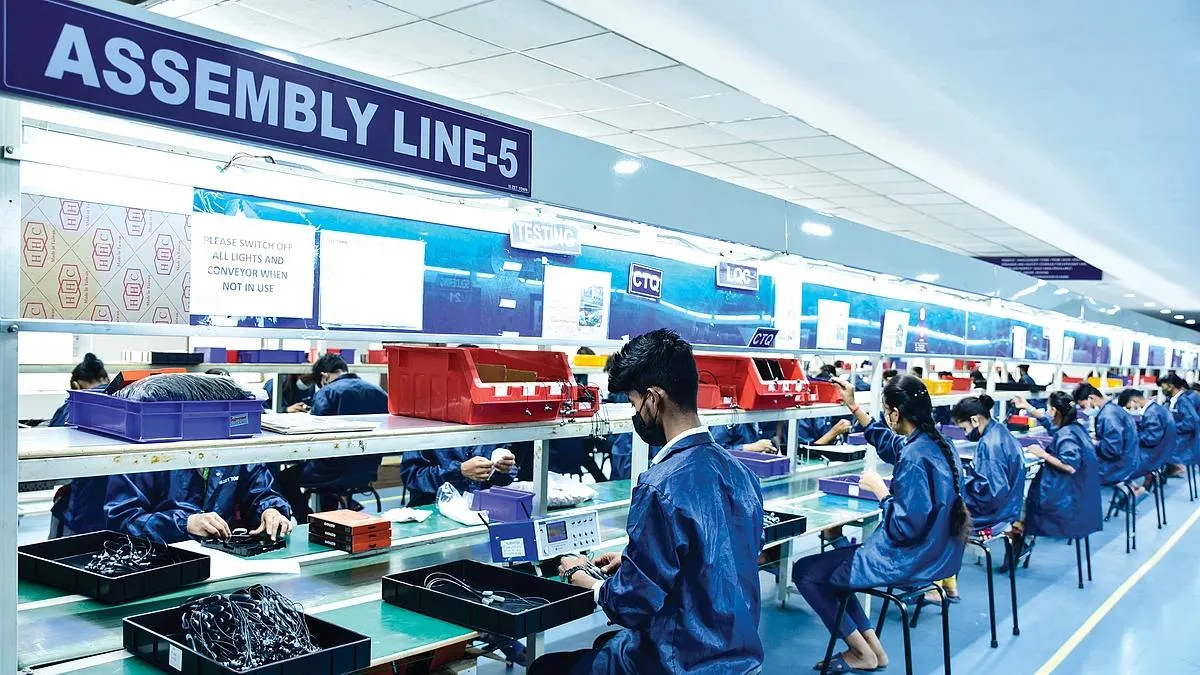
India has a vast manufacturing base comprising large corporations, specialized industrial groups, and numerous small and medium-sized production facilities. Many possess competitive technical expertise and equipment, yet their access to major international customers remains limited.
The difficulty does not necessarily lie in their ability to manufacture a component. It also involves winning contracts, satisfying qualification procedures, financing orders, meeting delivery schedules, and maintaining consistent quality.
Zetwerk operates precisely within this gap.
The company seeks to aggregate dispersed manufacturing capacity and present it to customers as a coordinated industrial system. It does more than connect buyers and suppliers: its model involves taking broader responsibility for order execution.
The distinction is fundamental.
A conventional commercial platform may earn a commission on a transaction. An industrial coordinator must ensure, according to the relevant contractual arrangements, that products are actually manufactured, inspected, and delivered.
It may therefore assume part of the production risks, contractual obligations, and financing requirements associated with industrial operations.
Zetwerk does not represent manufacturing liberated from physical constraints. Rather, it represents an attempt to centralize commercial and operational responsibility for production that remains distributed among multiple participants.
An Industrial Company Whose Assets Tell Only Part of the Story
Zetwerk's model should not be confused with that of a purely digital company.
It operates in sectors where technical requirements, equipment, and qualification procedures remain decisive. Its activities include energy, electronics, precision engineering, and defense.
The company also possesses manufacturing capabilities of its own, alongside production entrusted to external partners. The precise distribution between in-house manufacturing and outsourced production is one of the essential elements in assessing its economic model.
The underlying principle nevertheless involves separating, wherever possible, ownership of production assets from their coordination.
In traditional manufacturing, growth often requires building new facilities, purchasing machinery, hiring employees, and committing capital for several years before achieving satisfactory production volumes.
A network-based model can theoretically increase output more rapidly by mobilizing existing capacity.
This flexibility is particularly valuable when orders are irregular, products require several industrial specializations, or customers wish to avoid dependence on a single manufacturer.
It also makes geographical diversification possible without systematically reproducing the full investment required for an integrated factory.
But this arrangement comes with a trade-off.
A company that does not directly own all its manufacturing assets does not necessarily control its suppliers' priorities, investments, financial condition, or availability during periods of strong demand.
It must therefore compensate for reduced ownership control through superior coordination, contractual management, and oversight.
Much of Zetwerk's economic proposition rests on this capability.
The question is whether it can generate margins sufficiently attractive to compensate for the risks it concentrates.
Energy as the Primary Growth Engine
The figures released in connection with the planned IPO suggest that Zetwerk's expansion is not evenly distributed across industrial sectors.
Energy-related products reportedly account for approximately 60% of revenue, while precision products contribute around 23%.
This concentration helps explain the nature of its growth.
The global energy industry is undergoing a period of substantial investment. The development of electricity grids, renewable generation capacity, production equipment, and associated infrastructure is creating significant demand for metal components, industrial structures, and technical assemblies.
Wind power is one market where manufacturing requirements are particularly substantial. Installations depend on large structures, mechanical components, and equipment subject to demanding technical specifications.
Producing these elements may involve several specialized companies whose capabilities are not necessarily integrated within a single industrial group.
An organization capable of coordinating these manufacturers can therefore become a strategic supplier to major customers.
Yet this sectoral exposure also creates vulnerability.
Energy investment depends on public policy, financing conditions, equipment prices, and decisions made by a relatively limited number of major industrial players.
Changes in subsidies, slower orders, or pricing pressure can quickly affect subcontractors' volumes and margins.
Zetwerk's diversification into precision engineering, electronics, and defense may gradually reduce this dependence. It does not, however, guarantee that these businesses will display the same economic characteristics.
Defense equipment, for example, involves certification, traceability, and security requirements that can limit the flexibility of supplier networks.
Industrial growth is therefore not simply a matter of adding new sectors. It requires developing operational capabilities suited to each one.
Spectacular Growth, Profitability Still Fragile
The financial results presented for the April–June 2026 quarter illustrate both the speed of Zetwerk's expansion and the limitations of its model.
Operating revenue reportedly reached 41.18 billion rupees, representing year-on-year growth of more than 55%.
That is remarkable growth for a company operating in industrial activities where production lead times, investment requirements, and order cycles can be lengthy.
But it does not, by itself, demonstrate economic profitability.
The company reportedly recorded an adjusted quarterly loss of approximately 641 million rupees from continuing operations, compared with 8.81 billion rupees a year earlier.
The reduction in losses is substantial. It suggests improving financial performance without establishing that the business has reached economic equilibrium.
Relative to quarterly operating revenue, the adjusted loss represents approximately 1.6% of sales. This provides an indication of scale, but it should not be treated as a statutory net margin without examining the adjustments involved.
The central issue lies in the economics of industrial contracts.
When a company coordinates an order worth several million dollars, it may record substantial revenue while retaining only a relatively modest share of that value after paying manufacturers, purchasing materials, arranging transportation, and covering other operating expenses.
Revenue growth can therefore substantially exceed earnings growth.
This characteristic fundamentally distinguishes industrial platforms from the most profitable digital platforms.
In software services, adding another customer may involve relatively low marginal costs. In manufacturing, every additional order requires materials, labor, production capacity, and logistics.
Even when the company does not own the factories, these costs remain. They are simply borne and distributed differently.
Profitability consequently depends on negotiating purchasing terms, limiting defects, reducing delays, and retaining a sufficient share of contractual value.
In other words, coordination efficiency must produce a genuine economic advantage. Technology alone cannot transform a low-margin industrial activity into a highly profitable business.
The Working Capital Trap
Another constraint deserves particular attention: working capital requirements.
In many industrial contracts, suppliers must be paid before the final customer has fully settled the order.
Raw materials are purchased, manufacturing operations begin, and products are transported before final payment is received.
When a company acts as the principal coordinator of these operations, it may have to finance part of this timing difference.
Rapid revenue growth can therefore lead to higher receivables, inventories, or advances to suppliers.
Growth consumes cash before generating liquidity.
This mechanism can become particularly restrictive in sectors involving large orders and extended execution periods.
Zetwerk's IPO should be examined in this context.
Part of the announced proceeds is reportedly intended for debt repayment and new acquisitions.
Reducing debt can improve the company's financial structure and lower interest expenses. Acquisitions, meanwhile, can strengthen technical expertise, expand the customer portfolio, or enable greater integration of certain activities.
But these objectives follow different economic logics.
The first seeks to reduce accumulated financial risks. The second requires additional capital commitments, together with their own integration and profitability risks.
It will also be necessary to distinguish newly issued shares from existing shares potentially sold by current shareholders.
In the first case, the proceeds enter the company's accounts. In the second, the money goes to the selling shareholders.
An offering described as raising $518 million does not therefore necessarily mean that Zetwerk will receive that amount to finance its operations.
The final breakdown of the offering is essential to assessing its financial significance.
India Seeks to Move Beyond Its Role as a Manufacturing Base
Zetwerk's development forms part of a broader transformation of the Indian economy.
For several years, New Delhi has sought to strengthen manufacturing's position within its productive economy and international trade.
Production-linked incentive programs, infrastructure investment, and efforts to attract foreign manufacturers are all part of this strategy.
The objective is twofold: create industrial employment and reduce the country's dependence on imports of higher-value manufactured goods.
But India cannot simply reproduce China's development model.
Over several decades, China built an industrial ecosystem of exceptional density. Its major manufacturing centers bring together suppliers, subcontractors, logistics infrastructure, technical expertise, and financing capacity.
This proximity reduces lead times, facilitates production adjustments, and enables particularly efficient integration of supply chains.
India possesses different advantages: a vast domestic market, a large workforce, engineering and information technology expertise, and a private sector capable of developing complex industrial services.
It must nevertheless contend with regional disparities, unevenly developed infrastructure, and a supplier base whose capabilities are sometimes geographically dispersed.
Zetwerk's model can be interpreted as an entrepreneurial response to this fragmentation.
Rather than waiting for fully integrated industrial clusters to emerge organically, the company attempts to organize existing manufacturing capacity so that it can compete for larger contracts.
This approach does not replace investment in factories, transportation, or energy. It may nevertheless improve utilization of the productive infrastructure already available.
It could also facilitate the integration of Indian manufacturers into international value chains where contractual and technical requirements often constitute significant barriers to entry.
The challenge extends beyond increasing exports.
It is about determining whether Indian companies can become architects of international manufacturing networks rather than remaining merely the executors of orders designed and organized elsewhere.
The Real Prize: Controlling the Customer Relationship
In global value chains, the distribution of profits does not necessarily correspond to the distribution of manufacturing volumes.
A company may produce a substantial share of an industrial product without controlling its design, brand, market access, or commercial relationship with the final customer.
Conversely, some corporations capture a considerable share of value by controlling technical specifications, intellectual property, orders, and distribution channels.
Industrial subcontracting lies at the center of this asymmetry.
Manufacturers often bear the physical investments, labor costs, and part of the operational risks, while principal contractors retain a dominant position in commercial negotiations.
Zetwerk seeks to occupy an intermediate position that could alter this distribution.
By bringing together multiple suppliers, organizing their production, and becoming the customer's primary counterpart, it may acquire greater negotiating power than an individual manufacturer.
It can also accumulate information about available capacity, production costs, supplier performance, and recurring purchasing requirements.
This information can constitute a competitive advantage if it helps improve prices, quality, and delivery times.
But that advantage remains conditional.
Major industrial customers have powerful procurement departments and sophisticated supplier management systems of their own.
They may seek to reduce dependence on an intermediary that becomes too important or bring certain coordination functions back in-house.
Meanwhile, manufacturing partners may develop direct commercial relationships with customers.
Zetwerk's position is therefore sustainable only if it delivers operational value that competitors cannot easily replicate.
Its real strategic asset is not simply its supplier database. It is its ability to make that network operate more reliably than customers could achieve on their own.
Global Diversification Does Not Guarantee Industrial Independence
The geopolitical environment reinforces the appeal of this model.
Trade tensions between the United States and China, technology restrictions, logistical risks, and economic security policies are encouraging many companies to diversify their sources of supply.
The strategy commonly described as China plus one reflects this desire to reduce the geographical concentration of certain manufacturing activities.
India is among the countries positioned to benefit from this shift.
But moving an order to another country does not automatically transform a supply chain.
A factory located in India may still depend on Chinese components, European machinery, American software, or raw materials originating elsewhere.
Geographical diversification of assembly therefore does not guarantee industrial autonomy.
Companies capable of coordinating multiple suppliers can facilitate this transition, provided they understand precisely where components originate and which dependencies remain.
This requirement becomes particularly important in strategic industries.
Energy, defense, and electronics are not governed exclusively by cost considerations. Governments and industrial customers also seek to secure product origins, material traceability, and continuity of supply.
For Zetwerk, this evolution represents both a commercial opportunity and a source of additional constraints.
The more geopolitically sensitive industrial supply chains become, the more their coordination requires sophisticated controls, compliance procedures, and risk management.
An industrial platform cannot therefore rely solely on speed and competitiveness. It must also become verifiable and dependable.
A New Category of Company, or an Old Business Modernized?
The language surrounding industrial platforms sometimes presents their emergence as a disruption comparable to that created by major digital platforms.
The comparison requires caution.
Supplier coordination, outsourced production, and manufacturing network management existed long before digital platforms appeared.
Large industrial corporations, trading companies, and contract manufacturers have built substantial businesses around these principles.
What may be changing is the ability of information systems to make coordination faster, broader, and more precise.
Industrial data collection, digital order tracking, automation of certain procedures, and production capacity analysis can reduce transaction costs.
They may also allow a company to work with more suppliers without proportionately increasing its administrative workforce.
But economies of scale must be demonstrated.
An industrial platform that multiplies its orders without improving margins, cash generation, or productivity does not necessarily create a superior business model.
It may simply become a larger intermediary carrying greater risks.
The distinction between genuine industrial transformation and commercial modernization will therefore depend on observable results.
Investors will need to examine the evolution of gross margins, operating earnings, cash flows, debt, and capital tied up in the business.
Revenue concentration among major customers, dependence on particular sectors, and the share of production carried out in company-owned facilities will also be decisive.
These indicators will help determine whether Zetwerk is building an industrial position that is difficult to replace or whether its growth primarily reflects increasing order volumes.
The Stock Market as a Test of Reality
The IPO planned for October 2026 comes at a time when India is seeking to strengthen its position as a manufacturing power.
For Zetwerk, it could provide additional financial resources, improve visibility, and facilitate international expansion.
But it will also subject the company to a different discipline.
Investors cannot indefinitely be satisfied with rapid revenue growth. They will want to determine whether that growth generates recurring profits and sufficient cash flow.
The targeted valuation of $2.64 billion will need to be assessed against that earnings potential, rather than simply the volume of orders handled.
Zetwerk's case thus exposes a contradiction characteristic of contemporary manufacturing.
Companies seek to reduce fixed assets, make sourcing more flexible, and distribute risks among multiple partners. Yet manufacturing remains a physical, capital-intensive activity, constrained by quality requirements, payment terms, and production uncertainties.
Coordination can improve the efficiency of this organization. It does not eliminate its fundamental costs.
Zetwerk's ambition is precisely to demonstrate that a company can build a sustainable industrial advantage by controlling order execution without necessarily owning all the assets required to manufacture the products.
If it succeeds, its development could illustrate an important evolution in India's position within the global economy: that of a country capable not only of hosting manufacturing capacity, but also of organizing international production networks.
If it fails to convert growth into sustainable profitability, it will reaffirm a less novel reality: in manufacturing, risks do not disappear when they are distributed among several companies.
They simply move elsewhere.
Zetwerk's future will therefore depend less on the number of factories it can mobilize than on the value it manages to retain by making them work together.
And this may be where part of the next stage of India's industrialization will unfold: no longer merely manufacturing for the world, but deciding how the world manufactures.
Main Sources
Reuters, October 12, 2026 — India's Zetwerk sets price band of 143–151 rupees per share for $518 million IPO. Information concerning the offering timetable, targeted valuation, financial performance, and announced use of proceeds.
Zetwerk — Investor Relations. Company financial and regulatory documentation, subject to consultation and confirmation of the final IPO documents.
Government of India — Ministry of Commerce and Industry. Institutional documentation concerning industrial policy, manufacturing development, and investment incentive programs.
World Bank — World Development Indicators. Structural data on manufacturing, investment, and India's integration into the global economy.
World Trade Organization — World Trade Report. Analysis of global value chains, supply chain diversification, and production fragmentation.
Editorial note: The financial figures and IPO terms cited in this article are based on information reported for October 12, 2026. The final prospectus, breakdown between newly issued and existing shares, cash flow figures, and detailed profitability indicators have not been independently verified in preparing this article. The discussion of the model's advantages and limitations constitutes economic analysis rather than performance already demonstrated by Zetwerk.
Atlas Limits Research Desk
Atlas Limits’ editorial and analytical desk.