By finalizing a $5.1 billion financing package for Alliant Energy, Washington is doing more than supporting the construction of new electricity infrastructure. The United States is redefining the criteria through which federal financial power is deployed to shape its energy system. Behind the transaction lies a deeper transformation: in an economy where artificial intelligence, data centers, and strategic industries are driving electricity demand, access to reliable power is becoming a decisive determinant of national competitiveness.
A Financial Transaction That Extends Beyond the Electricity Sector
On October 28, 2026, the U.S. Department of Energy announced the closing of a $5.1 billion federal financing package benefiting Alliant Energy, an American utility group operating primarily in Iowa and Wisconsin.
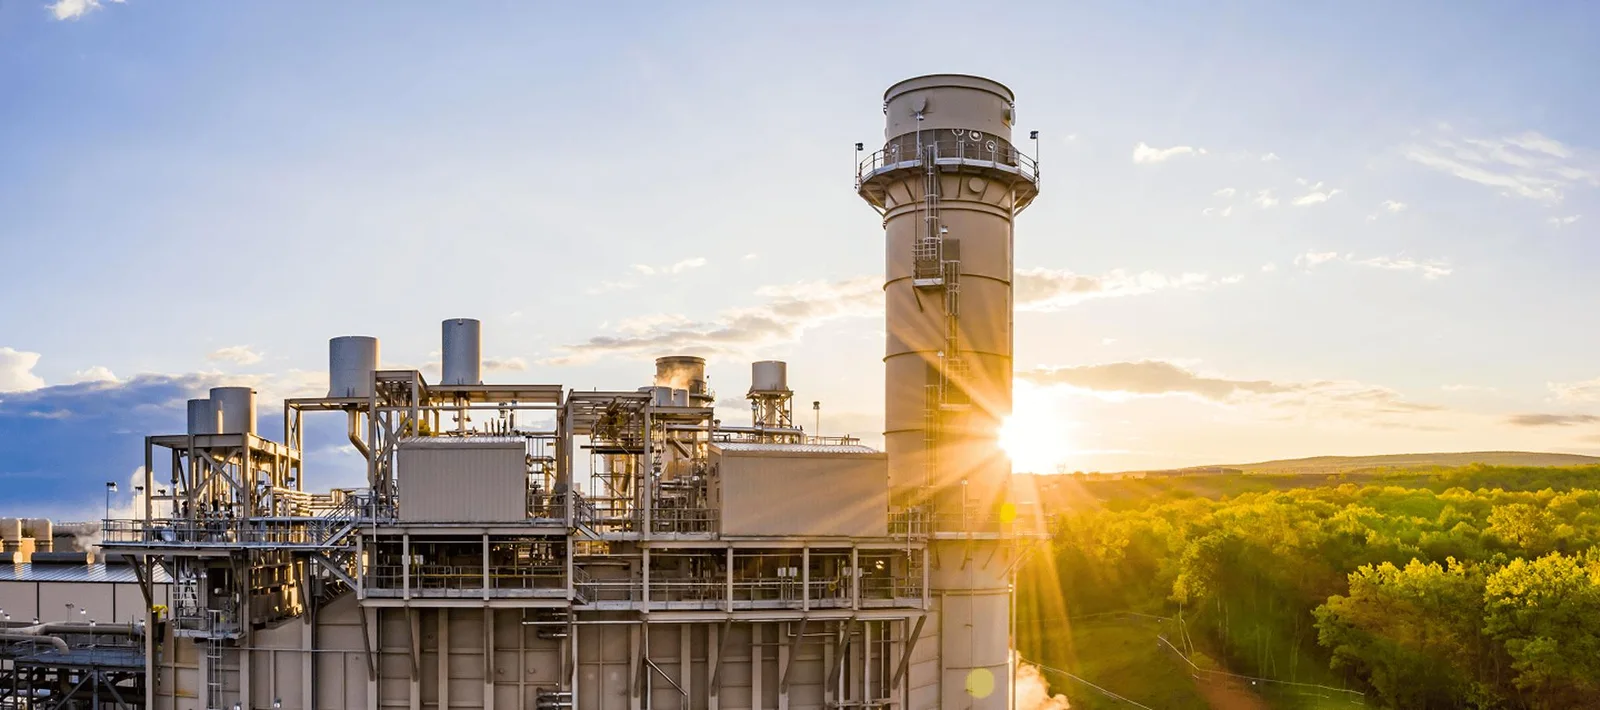
The transaction will support investments in new natural gas-fired power plants, energy storage facilities, and the modernization of existing electricity generation assets.
According to the announced figures, the projects will create or modernize more than 2.6 gigawatts of electricity generation capacity.
For perspective, this amount of capacity has been presented as theoretically sufficient to serve approximately 1.8 million American households.
Such comparisons, however, should not be confused with actual annual electricity production, which depends on the technologies deployed, operating conditions, and capacity utilization.
The investments are also expected to support hundreds of construction-related jobs.
Yet the significance of the transaction lies neither exclusively in its size nor in the physical infrastructure it will finance.
It reflects a broader change in the relationship between federal energy policy, industrial competitiveness, and capital allocation.
The financing has now reached financial close.
It is no longer merely a conditional commitment, although financial closing does not necessarily mean that the entire amount has already been disbursed or that the underlying facilities are operational.
This distinction matters.
Washington is not acquiring a $5.1 billion equity stake in Alliant Energy.
Instead, it is deploying federal debt-financing mechanisms to support infrastructure investments whose economic consequences will unfold over several decades.
The federal government is therefore influencing capital allocation without necessarily changing corporate ownership.
From $3 Billion to $5.1 Billion: The Transformation of an Initial Commitment
The origins of the transaction predate its finalization.
On January 16, 2025, during the final days of the Biden administration, the Department of Energy's Loan Programs Office announced conditional loan-guarantee commitments totaling more than $3 billion for Alliant Energy subsidiaries.
At that stage, the financing was primarily intended to support renewable electricity generation and energy storage investments in Iowa and Wisconsin.
The initial program was associated with approximately 2,000 megawatts of additional generation and storage capacity over the following decade.
Its financial rationale centered on reducing capital costs for investments contributing to the transformation of the electricity system.
The October 2026 closing takes place in a different political and energy environment.
The financing package now reaches $5.1 billion, approximately 70% above the initial $3 billion reference.
That increase should not automatically be interpreted as cost inflation affecting an unchanged portfolio of projects.
The scope of the investments has evolved.
More importantly, the composition of the infrastructure receiving federal support has changed.
While the original commitment emphasized renewable generation and storage, the finalized financing package includes natural gas-fired electricity generation and modernization of existing facilities.
Energy storage remains part of the program.
The shift therefore does not represent a simple replacement of one energy system with another.
It reflects a change in the relative importance assigned to several objectives: decarbonization, reliability, dispatchable capacity, infrastructure availability, and cost management.
Under this approach, the ability to produce electricity when the grid requires it is receiving greater political and financial attention.
The Return of Federal Financial Power to Energy Infrastructure
One of the transaction's most consequential features concerns the institution providing the financing.
Under the Biden administration, the Department of Energy's Loan Programs Office was particularly associated with supporting emerging energy technologies, low-carbon industrial projects, and investments facing obstacles to securing private financing on acceptable terms.
Under the Trump administration, the office operates under the name Office of Energy Dominance Financing.
The institutional change accompanies a shift in financing priorities.
Federal financial instruments are being used more explicitly to support conventional energy infrastructure, including natural gas-fired power generation.
This development raises a fundamental question of economic policy.
Under what circumstances should the federal government use its borrowing capacity and credit instruments to finance investments that private markets could, in principle, undertake independently?
Historically, public intervention in large industrial projects has rested on several economic justifications.
It can reduce risks that private investors are unwilling to assume.
It can accelerate infrastructure considered strategically important.
It can also address situations in which the broader economic benefits of an investment exceed the returns available to its private sponsors.
However, when public financing supports mature technologies such as natural gas-fired power generation, the economic justification becomes more complex.
Natural gas power plants already operate within established financial markets, industrial supply chains, and commercial business models.
Federal intervention therefore does not necessarily reflect an absence of private capital.
It may instead be designed to reduce financing costs, accelerate construction schedules, or influence the technological choices of electricity producers.
That distinction is fundamental.
The federal government is not simply supporting technologies that depend on public intervention for their development.
It is also using financial instruments to favor infrastructure considered important to its energy and industrial strategy.
Financing becomes an instrument of industrial policy.
Electricity Is Becoming a Core Infrastructure of Economic Power
The transformation comes as the United States faces a significant change in its electricity requirements.
For several decades, American electricity consumption grew relatively slowly, supported by improvements in energy efficiency and structural changes in the economy.
That pattern is evolving.
The expansion of data centers, artificial intelligence, industrial electrification, and investment in advanced manufacturing is generating additional electricity demand.
Digital infrastructure is particularly important.
A data center designed to train or operate advanced artificial intelligence systems requires substantial electricity supplies.
More importantly, it requires reliable and predictable access to power.
Electricity availability is becoming a prerequisite for deploying computing infrastructure.
Technology companies may possess considerable financial resources, advanced processors, and suitable industrial land while remaining unable to expand at their intended pace because electricity connections take years to secure.
The challenge therefore extends beyond energy prices.
It concerns grid capacity, connection delays, generation availability, and security of supply.
This development is changing the relationship between the energy industry and the digital economy.
Electricity infrastructure has traditionally been viewed as an essential service supporting economic activity.
In some regions, it is becoming a binding constraint capable of determining where industrial and technological investment takes place.
Computing power increasingly depends on the availability of physical electrical power.
This relationship creates a new form of interdependence between utilities, grid operators, technology companies, and public authorities.
Energy investment can no longer be assessed independently of national industrial strategy.
Why Natural Gas Is Regaining Strategic Importance
The decision to support natural gas-fired power plants reflects the growing importance of dispatchable electricity generation.
Unlike wind and solar facilities, whose output depends on weather conditions, natural gas plants can adjust production in response to system requirements, subject to their technical limitations and fuel availability.
This characteristic provides important operational advantages for electricity networks experiencing rising demand or significant fluctuations in consumption.
Combined-cycle gas plants can deliver relatively efficient electricity generation.
Certain gas turbines can also provide flexibility during periods of peak demand.
Natural gas can therefore perform several functions within an electricity system.
It can supply a portion of regular generation.
It can complement renewable electricity when wind or solar output declines.
It can also contribute to maintaining grid stability during periods of elevated demand.
These advantages do not mean that natural gas is necessarily the cheapest or fastest solution in every circumstance.
Building new gas-fired facilities requires regulatory approvals, equipment procurement, fuel transportation infrastructure, and grid connections.
Operating costs remain exposed to fluctuations in natural gas prices.
The facilities also generate carbon dioxide emissions, while the broader natural gas supply chain can produce methane emissions.
The economic attractiveness of gas therefore depends on its specific role within the electricity system, its utilization rate, and the alternatives available.
For Alliant Energy, the strategic value of federal financing lies partly in supporting several complementary categories of infrastructure.
Natural gas facilities can provide dispatchable generation.
Energy storage can shift electricity availability toward periods of greater demand.
Modernization of existing equipment can improve performance or extend the productive life of assets already connected to the grid.
Together, these investments may provide a more diversified response to electricity reliability challenges than a strategy concentrated exclusively on one technology.
Their effectiveness will nevertheless depend on the precise composition of the projects, construction schedules, and integration into regional electricity networks.
Iowa and Wisconsin: Industrial Regions Facing New Electricity Requirements
The geographic concentration of the financing is also significant.
Iowa and Wisconsin belong to a region whose economy depends heavily on agriculture, manufacturing, logistics, and industrial production.
These states also operate electricity systems facing modernization requirements and changing consumption patterns.
Alliant Energy serves these markets through regulated utility businesses.
This business model differs from that of an independent electricity producer relying exclusively on wholesale power markets.
Investments made by regulated utilities may, subject to regulatory approval, become part of the asset base used to determine authorized electricity rates.
Public utility commissions therefore play an important role in the financial economics of infrastructure development.
They assess investment requirements, costs, and the implications for consumers.
This regulatory framework can provide greater visibility over future revenue streams.
It does not eliminate construction risks or regulatory uncertainty.
An investment financed on favorable terms may still prove economically inefficient if the resulting capacity exceeds actual demand or if final costs become excessive.
Conversely, prolonged underinvestment in electricity infrastructure can constrain regional economic development and increase reliability risks.
The central question is therefore which combination of infrastructure investments can satisfy future electricity requirements at the lowest sustainable overall cost.
This calculation becomes particularly important when the same electricity system must serve households, established businesses, and large new industrial consumers.
Federal Debt Financing as an Instrument of Competitiveness
The financing structure is another central dimension of the transaction.
Long-term public financing can offer several potential advantages to utilities undertaking capital-intensive investment programs.
The first concerns financing costs.
When federal financing terms are more favorable than those available in private capital markets, companies may reduce interest expenses over the life of their borrowing.
The second concerns debt maturity.
Electricity infrastructure requires substantial upfront investment, while the resulting economic returns generally accumulate over several decades.
Long-term financing can improve the alignment between debt repayment schedules and the productive life of infrastructure assets.
The third advantage concerns investment planning.
By securing part of its financing requirements, a utility can gain greater visibility over construction schedules, equipment procurement, and industrial contracting.
These potential advantages must nevertheless be distinguished from demonstrated financial results.
The publicly available information accompanying the announcement does not establish the precise interest rates, maturities, collateral arrangements, or final financing savings associated with every component of the package.
It would therefore be premature to calculate the transaction's definitive net economic benefits.
Financial closing is an important milestone.
It is not, by itself, proof that the underlying investments will generate higher returns or permanently reduce electricity costs.
Nor does it establish that consumers will automatically benefit from lower utility bills.
Any savings will depend on actual financing costs, operating expenses, regulatory decisions, and the distribution of economic benefits.
The distinction between cheaper financing and cheaper electricity must remain clear.
A Transaction That Changes the Distribution of Risk
Federal financing can also alter the distribution of risk among economic participants.
For Alliant Energy, it may reduce certain financial uncertainties and facilitate the execution of its investment program.
For private investors, it may improve visibility over the company's financing requirements.
For electricity consumers, it creates the possibility of lower capital costs than would otherwise have been incurred through exclusively private financing.
For the federal government, however, the transaction creates financial exposure that must be assessed against contractual protections and credit risks.
A government-supported loan does not have zero economic cost.
Public authorities commit financial capacity, assume obligations, and must manage the possibility that projects will not perform as originally expected.
This consideration becomes particularly important when the financed infrastructure is exposed to long-term technological change.
A power plant may be designed to operate for several decades.
Over such a period, fuel prices, storage technologies, environmental requirements, and electricity demand can change substantially.
Investment decisions taken today may therefore influence the structure of the electricity system long after the current political cycle has ended.
The issue extends beyond immediate financing.
It concerns how long-term risks are distributed among companies, shareholders, consumers, and the public sector.
The Paradox of an Energy Strategy Built Around Abundance
The emerging American energy strategy places considerable emphasis on expanding energy supply to support economic growth and limit price pressures.
The industrial logic is understandable.
When electricity demand rises rapidly, insufficient available capacity can contribute to higher prices, delay investment, and weaken grid reliability.
Increasing supply can help address these constraints.
However, energy abundance does not result simply from adding more power plants.
Electricity must be available in the right location, at the right time, and at an economically sustainable cost.
A new generating facility in a region with insufficient transmission infrastructure may do little to resolve shortages elsewhere.
Similarly, expanding installed capacity does not guarantee lower electricity bills if infrastructure costs rise faster than the economic benefits generated.
New generation must therefore be coordinated with investment in transmission networks, storage, demand management, and existing facilities.
This coordination represents one of the central challenges facing American energy policy.
The objective of reliable electricity supply can be shared by policymakers and companies supporting different technological approaches.
Their disagreements often concern how reliability should be achieved, who should bear the costs, and what environmental consequences are acceptable.
The central issue is therefore not simply whether natural gas should prevail over renewable energy.
It is which combination of infrastructure can meet electricity demand over time while maintaining acceptable levels of financial, operational, and environmental risk.
Nuclear Energy and the Broader Federal Financing Strategy
The Alliant Energy transaction is not an isolated development.
It forms part of a broader sequence of federal financing initiatives targeting electricity infrastructure.
On October 27, 2026, the Department of Energy announced a conditional commitment of up to $5 billion to support modernization projects at nuclear facilities operated by Constellation Energy.
The proposed investments are intended to increase output from existing reactors and strengthen generation capacity without necessarily requiring entirely new nuclear plants.
Other federal initiatives have supported projects involving nuclear plant life extensions, restarts, and performance improvements.
The comparison is revealing.
In the nuclear sector, federal financing can support dispatchable electricity generation with relatively low direct carbon emissions.
In Alliant Energy's case, the finalized package includes new natural gas-fired generation.
The technologies differ significantly.
Yet the transactions share a common strategic objective: expanding available electricity capacity and strengthening system reliability.
Federal energy policy is therefore becoming less exclusively organized around a distinction between clean and conventional technologies.
Greater attention is being directed toward the operational characteristics of infrastructure and its expected contribution to security of supply.
This does not mean environmental considerations have disappeared from investment decisions.
Rather, energy policy is increasingly being formulated around a broader set of industrial, economic, and strategic priorities whose relative importance has changed.
The Global Competition for Electricity Infrastructure
The implications extend beyond the United States.
Major industrial economies face a similar question: how can they guarantee sufficient electricity to support digital infrastructure and advanced manufacturing?
Their responses vary according to available resources, market structures, and political choices.
Some countries benefit from substantial hydroelectric capacity.
Others rely more heavily on nuclear power, fossil fuels, or accelerated renewable energy deployment.
Yet industrial competition creates a common pressure.
Companies considering investments in data centers, semiconductor manufacturing, or electricity-intensive industrial facilities must evaluate the energy infrastructure available in potential locations.
Electricity prices influence competitiveness.
Grid connection delays can determine investment schedules.
Network reliability affects operational continuity.
Under these conditions, public financing of electricity infrastructure can become a factor in competition between states.
A country capable of accelerating reliable electricity development may strengthen its attractiveness to industrial investors.
However, the advantage depends on the quality of the investments undertaken.
Expensive, underutilized, or technologically inappropriate infrastructure can impose lasting costs on businesses and consumers.
Public financial power is therefore not automatically a competitive advantage.
It becomes one when capital is efficiently directed toward infrastructure that responds to genuine economic requirements.
Alliant Energy and the Transformation of Infrastructure Capitalism
The transaction also illustrates a broader evolution in the financing of strategic infrastructure.
Across several sectors, the boundaries between private capital and public intervention are becoming more complex.
Companies remain privately owned.
Shareholders retain their ownership rights.
Management continues to make operational decisions within the applicable regulatory framework.
Yet part of the investment required for corporate expansion may depend on financing, guarantees, or incentives provided by public authorities.
This arrangement creates a form of financial partnership in which the state influences infrastructure development without necessarily becoming an owner.
Governments can pursue industrial objectives without nationalizing companies.
Businesses can access financing that changes the economics of their projects.
But the arrangement also raises governance questions.
How should beneficiaries be selected?
How should competing technologies be evaluated?
How can the economic benefits of public financing be measured?
How can governments avoid creating lasting advantages for particular companies at the expense of competitors?
And how can they ensure that the benefits of public financial support are not captured exclusively by shareholders?
These questions become especially important when financing commitments reach several billion dollars.
The Alliant Energy package does not represent a transfer of corporate control.
It nevertheless constitutes a significant intervention in the financial conditions governing the company's industrial development.
The federal government is influencing the cost and availability of capital, two fundamental determinants of investment decisions.
The Risks of Long-Term Infrastructure Commitments
The strategic importance of the transaction should not obscure the uncertainties surrounding implementation.
The first risk concerns construction costs.
Large energy projects are exposed to equipment price fluctuations, supply chain constraints, and shortages of specialized labor.
The second concerns project schedules.
Regulatory approvals, grid connections, and technical difficulties can delay the commissioning of new facilities.
The third concerns natural gas prices.
Even when financing costs are favorable, the economics of gas-fired power plants depend on operating expenses and energy market conditions.
The fourth concerns regulation.
Facilities constructed today will operate in an environment that may experience changes in environmental requirements, market rules, and technical standards.
The fifth concerns demand.
Expected growth in electricity consumption, particularly from data centers, may justify additional generating capacity.
But the pace, geographic distribution, and composition of that growth remain uncertain.
Demand growth below expectations could reduce the utilization of some assets.
Faster-than-expected growth could require additional investment.
Technological developments may also alter the relative competitiveness of different energy solutions.
Advances in storage, intelligent electricity networks, flexible demand management, and alternative generation technologies could change the economics of conventional power plants.
The fundamental difficulty lies in the difference between two time horizons.
Industrial demand can evolve rapidly.
Electricity infrastructure is financed and operated over decades.
An effective energy strategy must reconcile these timelines.
The Central Question: Who Will Finance the Electricity Behind the Next Industrial Revolution?
The Alliant Energy financing package reveals a deeper transformation in the relationship between energy, finance, and industrial power.
Artificial intelligence is frequently described as a revolution driven by algorithms, data, and semiconductors.
But its expansion also depends on substantial physical infrastructure.
Data centers require land, cooling equipment, communications networks, and reliable electricity supplies.
Investment in computing capacity therefore generates additional investment requirements across other sectors.
This interdependence is changing the geography of economic value.
A technology company may control advanced artificial intelligence models without controlling the electricity infrastructure required to operate them.
A region may possess significant industrial capabilities without having the grid capacity needed to accommodate new facilities.
A government may encourage private investment while discovering that its realization depends on public decisions concerning energy infrastructure.
Financing consequently becomes central.
Utilities must mobilize substantial capital before receiving the revenues associated with new facilities.
Private financial markets can support these investments, but financing conditions depend on interest rates, perceived risks, and expected returns.
Public authorities possess instruments capable of changing those conditions.
By finalizing a $5.1 billion financing package, Washington is demonstrating its willingness to deploy those instruments in support of electricity infrastructure considered strategically important.
The transaction does not prove that the policy will necessarily produce cheaper electricity.
Nor does it guarantee that every financed project will be economically optimal.
But it reveals an important direction: the federal government intends to influence how certain infrastructure investments supporting American growth are financed.
A New Definition of Energy Sovereignty
For much of modern economic history, a country's energy power was closely associated with its natural resources.
Oil, natural gas, and coal reserves represented strategic advantages.
The ability to produce and export those resources strengthened economic and geopolitical influence.
These factors remain important.
But the evolution of industrial systems introduces additional criteria.
Dispatchable electricity capacity, network quality, storage availability, and the ability to mobilize infrastructure investment are becoming essential components of energy power.
A country can possess substantial hydrocarbon resources while lacking the electricity infrastructure needed to support new industries.
Conversely, an economy with limited fossil fuel reserves can develop a competitive electricity system through an effective combination of technologies, infrastructure, and financing.
Energy sovereignty therefore extends beyond resource ownership.
It depends on the ability to transform resources, or alternative energy sources, into reliable and economically sustainable electricity services.
Within this system, capital becomes as strategically important as fuel.
The ability to finance infrastructure rapidly can determine how quickly an economy converts industrial ambitions into productive capacity.
The Alliant Energy transaction reflects precisely this evolution.
It demonstrates that Washington increasingly regards electricity infrastructure financing as part of its broader strategy of economic power.
Conclusion — America's Energy System Enters a New Financial Era
The $5.1 billion financing package for Alliant Energy represents considerably more than a program to modernize electricity infrastructure in two American states.
It illustrates a reorientation of federal energy financing toward an approach that places greater emphasis on electricity availability, grid reliability, and industrial requirements.
The transition from an initial conditional commitment exceeding $3 billion, primarily focused on renewable energy and storage, to a finalized $5.1 billion package incorporating natural gas generation reflects that change.
It does not signify the disappearance of low-carbon technologies from federal priorities, as parallel financing initiatives involving nuclear energy demonstrate.
Instead, it reveals a transformation in how Washington intends to combine energy security, industrial competitiveness, and capital mobilization.
The results will have to be assessed over time.
The actual commissioning of infrastructure, final construction costs, contributions to grid reliability, and consequences for electricity tariffs will determine the program's economic effectiveness.
Yet its strategic significance is already apparent.
In an economy where electricity availability is becoming a decisive factor in industrial and digital expansion, controlling energy resources is no longer sufficient.
Countries must also possess the financial capacity to build, modernize, and operate the infrastructure that makes those resources economically useful.
The next phase of global industrial competition will not be decided exclusively in artificial intelligence laboratories, semiconductor factories, or financial markets. It will also be shaped by power plants, transmission networks, and investment decisions determining where, when, and at what price electricity becomes available.
By mobilizing $5.1 billion for Alliant Energy, Washington is highlighting a fundamental reality: tomorrow's economic power will depend as much on the ability to finance electricity infrastructure as on the ability to invent the technologies that consume its output.
Atlas Limits Research Desk
Atlas Limits’ editorial and analytical desk.