Europe is no longer concerned solely with determining who can acquire its companies. It increasingly wants to understand how those acquisitions are financed, under what conditions they take place, and what consequences they may have for competition within its single market. The European Commission's conditional approval, granted on November 3, 2026, for Chinese e-commerce group JD.com's acquisition of Germany's Ceconomy illustrates this shift. Behind a transaction that remains relatively modest by the standards of major international mergers and acquisitions lies a much broader question: how far can the European Union preserve its openness to foreign capital while preventing economic advantages granted by third-country governments from permanently altering competitive conditions within its territory?
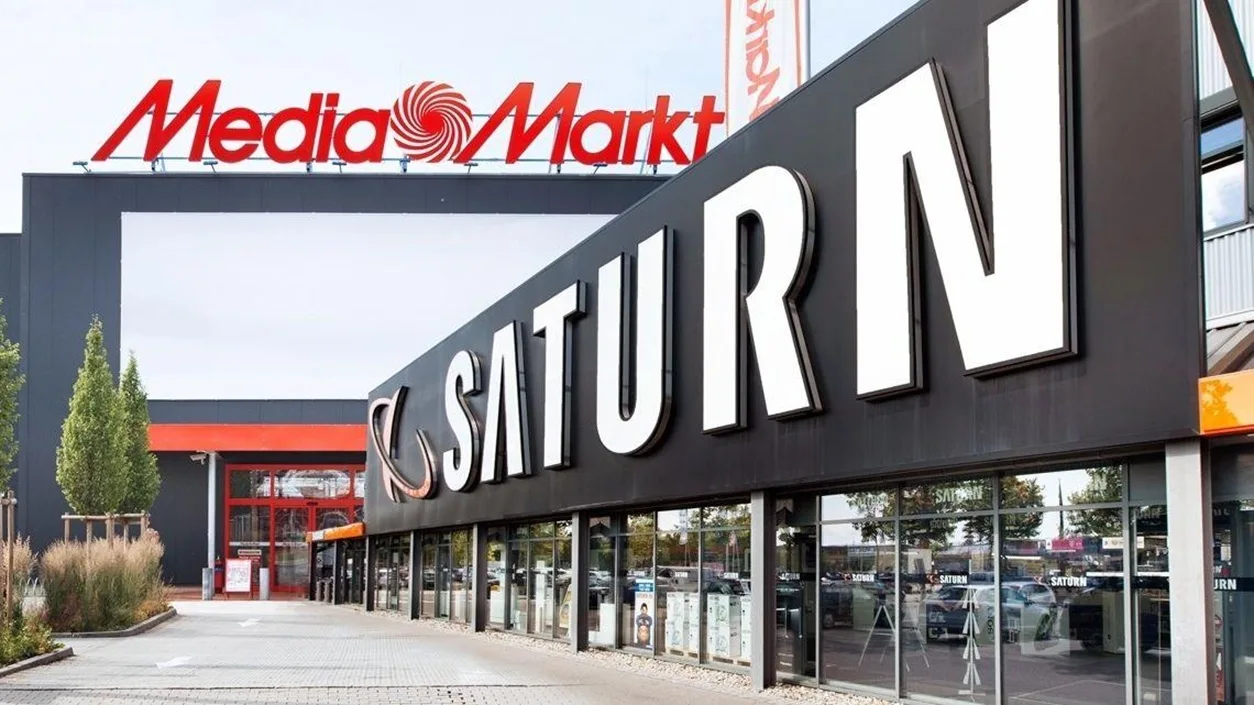
The transaction brings together two companies whose trajectories reflect different transformations of the global economy. On one side stands JD.com, a major Chinese e-commerce company that has built its development around the integration of retail distribution, logistics infrastructure, and digital technologies. On the other is Ceconomy, the German group behind MediaMarkt and Saturn, representing a significant part of Europe's consumer electronics retail industry. Their combination is therefore more than a commercial consolidation. It brings together two models of industrial organization, two regulatory environments, and two approaches to economic power.
By authorizing the acquisition while imposing commitments designed to preserve competition, Brussels is choosing neither unrestricted openness nor systematic prohibition. Instead, it is attempting to define the conditions under which companies benefiting from foreign public support may acquire control of European assets.
This approach could progressively reshape how major international corporations structure their acquisitions across the continent.
An Acquisition in Preparation Since 2025
The transaction originated in July 2025, when JD.com announced a public takeover offer for Ceconomy. The Chinese group proposed €4.60 per share in a deal valued at approximately $2.5 billion, according to Reuters.
For JD.com, the acquisition represents an opportunity to accelerate its expansion into the European market by relying on an established retail network, recognized brands, and longstanding relationships with major international consumer electronics manufacturers.
Ceconomy possesses assets whose strategic value extends well beyond its physical stores. Through MediaMarkt and Saturn, the group operates a substantial commercial network across several European countries, supported by digital platforms, distribution infrastructure, delivery capabilities, and relationships with a diverse customer base.
The strategic appeal of the acquisition lies precisely in the complementarity between these assets and JD.com's expertise in integrated logistics, automation, and e-commerce.
Consumer electronics retail is particularly exposed to technological change. Commercial margins are frequently under pressure, consumers can compare prices almost instantly, and manufacturers increasingly operate direct sales channels. Retailers must therefore invest continuously in information systems, warehouses, after-sales services, and delivery capabilities.
In this environment, competitiveness no longer depends exclusively on the size of a physical retail network. It increasingly rests on the ability to coordinate inventories, data, orders, and physical flows across multiple markets.
JD.com has developed considerable experience in precisely this form of integrated organization.
For Ceconomy, joining a group with such capabilities could provide an important means of transformation. For JD.com, the acquisition offers accelerated access to a European commercial infrastructure that would otherwise require many years to build organically.
Yet this economic complementarity also lies at the heart of the regulatory concerns surrounding the transaction.
Brussels Now Examines the Origins of Competitive Advantages
On November 3, 2026, the European Commission conditionally approved the acquisition following an assessment under the Foreign Subsidies Regulation, commonly known as the FSR.
This distinction is fundamental.
Traditional merger control primarily seeks to determine whether a merger or acquisition is likely to significantly reduce competition, particularly by creating or strengthening a dominant market position.
The Foreign Subsidies Regulation addresses a different question: can a company benefiting from financial advantages granted by a third-country government use those resources to acquire European assets or expand its operations under conditions that distort the functioning of the internal market?
Both mechanisms may apply to the same transaction, but they rely on different legal assessments.
The FSR, which began applying in 2023, was designed to address a longstanding asymmetry in Europe's regulatory framework. Financial assistance granted by EU member states to companies is subject to extensive scrutiny under European state aid rules. By contrast, support provided by governments outside the European Union previously lacked a comparable cross-sector regulatory framework.
This difference could create a paradoxical situation: a European company might be prohibited from receiving certain public advantages while a competitor established outside the Union could benefit from preferential financing or subsidies capable of strengthening its position within the same market.
The new regulation allows the Commission to investigate such situations, assess their competitive effects, and, where the legal conditions are met, impose corrective measures.
In the JD.com–Ceconomy case, European concerns focused in particular on financial advantages attributed to JD.com, including various forms of Chinese public support.
The issue was not simply whether these resources had facilitated the financing of the acquisition. It was also whether they could contribute, after the transaction, to artificially strengthening the competitiveness of the combined JD.com–Ceconomy business.
This distinction is essential. An acquisition may raise no major concerns regarding the market shares immediately combined while still creating difficulties related to the economic conditions under which the new group will operate.
The Real Issue: The Infrastructure of Commerce
The European decision becomes particularly significant when viewed against the transformation of the retail industry.
For decades, major retail chains built their competitive strength primarily on store locations, purchasing power, and relationships with manufacturers.
These factors remain important, but they no longer fully explain differences in competitiveness.
An increasing share of economic value now lies in the infrastructure that enables commerce to function: digital platforms, automated warehouses, inventory management systems, delivery networks, demand forecasting software, and operational optimization technologies.
These infrastructures generate substantial economies of scale.
A company capable of processing large volumes of orders can reduce certain unit costs, improve product availability, and shorten delivery times. When these advantages become sufficiently significant, they can strengthen its ability to attract new customers and further increase transaction volumes.
A cumulative mechanism can then emerge: scale improves efficiency, efficiency reinforces commercial attractiveness, and greater attractiveness generates additional scale.
This phenomenon is not unique to Chinese companies. It characterizes much of the contemporary global digital economy.
However, when a company also benefits from public support capable of reducing its financing costs or facilitating infrastructure development, competition authorities must examine whether its competitive advantages result exclusively from economic performance or are amplified by benefits capable of distorting the market.
In JD.com's case, the question is particularly important because of the integration between its commercial, logistics, and technology operations.
The acquisition of Ceconomy could allow some of these capabilities to be deployed across the European market on a substantial scale.
Such developments may generate genuine benefits for consumers, particularly through lower prices, improved product availability, and better service quality. But they may also create imbalances if infrastructure controlled by the combined group is used to favor certain activities at the expense of independent competitors.
It is precisely along this boundary between industrial efficiency and competitive distortion that Brussels is seeking to intervene.
Commitments Designed to Regulate Integration
The European authorization rests on commitments intended to address the risks identified by the Commission.
The first concerns economic relationships between the different entities within the group. Intragroup transactions must comply with market conditions, preventing certain services or resources from being transferred at artificially advantageous prices.
This requirement is intended to prevent financial advantages obtained in one part of the organization from being used to indirectly subsidize other commercial activities.
The second commitment concerns logistics services. JD.com must ensure non-discriminatory access for relevant third-party operators, within the scope of the commitments accepted by the Commission.
This dimension is particularly important.
Logistics has become an essential infrastructure for e-commerce. Companies operating the most efficient warehousing and delivery networks can enjoy substantial advantages over their competitors.
If these capabilities are reserved for selected retailers or offered under preferential conditions, they can become instruments of competitive foreclosure.
The third commitment concerns technology services. Its purpose is to prevent integration between JD.com and Ceconomy from resulting in certain technological advantages being reserved exclusively for the group's own retail network, where the commitments provide for comparable access by third-party retailers.
These obligations reflect a precise regulatory logic: allowing efficiency gains associated with industrial integration while limiting mechanisms that could transform that integration into an artificial competitive advantage.
The commitments are intended to remain in force for ten years and to be monitored independently under the European Commission's supervision.
This duration underscores that Brussels does not consider competitive risks to be confined to the moment of acquisition. They may materialize progressively as the logistics, technological, and commercial systems of the two companies become increasingly integrated.
The authorization is therefore more than a simple administrative clearance. It establishes a framework of obligations that will accompany the economic organization of the combined business over an extended period.
Europe and Chinese Capital
The JD.com–Ceconomy transaction forms part of an increasingly complex economic relationship between Europe and China.
China is simultaneously a major market, an industrial partner, an essential supplier within numerous value chains, and an increasingly significant competitor in technology-intensive sectors.
Chinese companies possess substantial capabilities in e-commerce, batteries, electric vehicles, industrial equipment, digital infrastructure, and manufacturing technologies.
Their international expansion serves several objectives: gaining access to new consumers, diversifying revenues, reducing dependence on the domestic market, and strengthening their presence in global value chains.
For Europe, these investments can contribute to corporate financing, industrial modernization, and the diffusion of new technologies.
Yet they also raise questions concerning competition, economic dependencies, technology transfers, and control over strategic assets.
The European Union is therefore seeking to develop an approach that does not rely exclusively on the nationality of foreign investors.
Its regulatory framework distinguishes several categories of risk.
Foreign direct investment screening mechanisms primarily address security and public order concerns. Merger control examines the effects of transactions on competition. The Foreign Subsidies Regulation focuses on distortions potentially resulting from financial support granted by third-country governments.
These instruments are not interchangeable.
However, when applied together, they allow an international acquisition to be examined from several perspectives.
In Ceconomy's case, the relevant foreign investment approvals had already been obtained in the European jurisdictions concerned before the November 3 decision.
The Commission's conditional approval under the FSR was therefore the final regulatory clearance required according to the parties, opening the way for a closing expected in the following days.
This sequence of reviews illustrates the growing complexity of cross-border transactions.
An investor must do more than demonstrate financial capacity and negotiate with shareholders. It must also be able to document the origins of certain economic advantages, explain how they are used, and, where necessary, accept restrictions on the future organization of its activities.
A New Variable in International Mergers and Acquisitions
The emergence of foreign subsidy control is progressively changing the economics of transactions.
In a conventional acquisition, the principal negotiating parameters generally concern valuation, financing, expected synergies, governance arrangements, and regulatory approvals.
The FSR introduces an additional dimension: the assessment of foreign financial contributions and their potential effects on the European market.
This development can influence transaction preparation long before a deal is publicly announced.
Relevant acquirers must identify financial support received, document relationships with public authorities, and assess the possible consequences of those advantages for their European operations.
Sellers, meanwhile, must consider the risk that certain offers may face additional regulatory reviews or commitments capable of changing the economic value of the transaction.
Financial and legal advisers are also required to incorporate these parameters into due diligence, transaction timetables, and regulatory risk assessments.
An acquisition can therefore no longer be evaluated solely on the basis of the price offered.
Two buyers proposing comparable valuations may present different regulatory profiles depending on their financing structures, exposure to foreign public support, and the synergies they intend to realize following the acquisition.
Corrective commitments may themselves alter the industrial rationale of a transaction.
Where an acquirer expects to generate savings through extensive logistics or technological integration, obligations to provide certain forms of third-party access or maintain comparable commercial conditions may limit some of the advantages initially anticipated.
This does not necessarily mean that the transaction loses its economic appeal.
But the value of expected synergies must be assessed in light of regulatory constraints.
Competition policy is thus becoming an increasingly important component of acquisition strategy.
Economic Sovereignty Through Regulation
Economic sovereignty is often associated with national ownership of companies, trade restrictions, or industrial support policies.
The European approach reveals a different conception.
In a market largely open to international capital, the ability to define operating rules can itself constitute a form of economic power.
The European Union does not necessarily possess dominant companies in every technological sector. It nevertheless represents a major consumer market, supported by a common legal framework and institutions capable of imposing obligations on operators seeking to conduct business within its territory.
This regulatory capacity allows Europe to influence the behavior of companies whose headquarters, shareholders, and principal infrastructure may be located far beyond its borders.
The JD.com–Ceconomy case provides a concrete illustration.
Brussels is not seeking to systematically prevent a European retailer from becoming part of a Chinese group. Instead, it intends to regulate the conditions under which that group's economic advantages may be transferred into the internal market.
The distinction matters.
A general prohibition on foreign investment could reduce financing opportunities and limit the transformation of European companies. Conversely, openness without corrective mechanisms could expose certain sectors to competitive imbalances that become difficult to reverse once market positions are consolidated.
The European strategy seeks to establish a balance between these two risks.
That balance remains difficult to achieve.
Excessively burdensome obligations could reduce the attractiveness of the European market for certain international investors. Insufficient obligations could allow lasting distortions to develop.
The effectiveness of the framework will therefore depend as much on the quality of initial assessments as on the authorities' ability to monitor commitments and intervene when their implementation fails to achieve the intended objectives.
The November 3 decision does not, by itself, establish whether this balance will ultimately be achieved. It does, however, demonstrate that Brussels increasingly intends to intervene in the economic conditions of integration, rather than focusing exclusively on the legal structure of acquisitions.
The Limits of Regulatory Sovereignty
The ability to impose rules should not, however, be confused with control over industrial capabilities.
The European Union can regulate market access, monitor competitive conditions, and impose commitments on foreign investors. These instruments are not necessarily sufficient to create European companies capable of competing with major international groups in logistics, digital commerce, or technological infrastructure.
The distinction is central.
Regulation can prevent certain distortions, but it cannot replace productive investment, innovation, or economies of scale.
In e-commerce, competitiveness depends on substantial investment in information systems, warehouses, delivery networks, and data analytics.
Companies that have developed these capabilities over many years possess advantages that are difficult to reproduce quickly.
The acquisition of Ceconomy by JD.com can therefore be interpreted in two complementary ways.
First, it demonstrates the attractiveness of the European market to international groups capable of mobilizing capital and technological expertise.
Second, it highlights the difficulties faced by some European companies in independently financing the transformations required for their future competitiveness.
The question of sovereignty consequently extends beyond the nationality of the owner.
It also concerns the location of technological capabilities, the operational autonomy of companies, control over data, infrastructure resilience, and the ability of European businesses to retain industrial expertise.
A company may remain legally European while depending heavily on foreign technologies or services.
Conversely, a company owned by foreign investors may retain substantial industrial activity, employment, operational decision-making centers, and innovation capabilities within Europe.
The analysis must therefore move beyond a simple opposition between domestic and foreign ownership.
It must examine actual dependencies, substitution capabilities, and the conditions under which economic value is created and retained.
A Precedent Worth Watching, Without Overstating Its Significance
The decision concerning JD.com and Ceconomy is not the first application of the European Union's Foreign Subsidies Regulation. It forms part of the gradual development of a regulatory practice covering acquisitions, public procurement, and other situations capable of affecting the internal market.
Its significance nevertheless lies in the nature of the transaction and the commitments adopted.
The case involves a Chinese group with substantial logistics and technological capabilities, an established European retailer, and obligations designed to regulate the future commercial relationships of the combined business.
It therefore provides an opportunity to observe how the Commission intends to address risks associated with the integration of several activities within a group benefiting from foreign financial contributions.
For international investors, the challenge will be to understand the circumstances under which similar commitments might be required.
For European companies, it will be to assess the consequences of these new constraints for financing conditions and asset valuations.
For public authorities, the difficulty will be to preserve fair competition without transforming foreign subsidy control into an instrument of economic discrimination.
In principle, the regulation is based on the existence and effects of foreign financial contributions, rather than a prohibition determined by an investor's nationality.
Its application will need to preserve this distinction to maintain legal coherence and international credibility.
An Open Europe, but a Less Passive One
The conditional approval of JD.com's acquisition of Ceconomy reveals a transformation that extends well beyond the two companies.
For several decades, the openness of European markets largely rested on the assumption that international capital flows promoted economic efficiency, investment, and competition.
That logic remains present within European institutions. But it now coexists with greater attention to the conditions under which international companies finance their expansion and organize their competitive advantages.
The change is not necessarily that Europe is closing itself off.
It is that Europe is increasingly seeking to distinguish economic openness from the absence of oversight.
The internal market remains accessible to foreign investors, including when acquisitions involve companies operating substantial commercial networks. But that access may be accompanied by obligations designed to prevent certain forms of external public support from permanently disrupting competition.
The JD.com–Ceconomy transaction is revealing in this respect.
It demonstrates that contemporary economic power no longer resides solely in corporate ownership or the ability to finance acquisitions. It also depends on control over infrastructure, the organization of value chains, and the capacity to define the conditions under which those systems operate.
For JD.com, the challenge will be to transform its European expansion into an industrial and commercial success while respecting the commitments it has accepted.
For Ceconomy, it will be to benefit from the capabilities of its new shareholder without losing the advantages that have made its retail network valuable.
For Brussels, it will be to demonstrate that a more demanding competition policy can protect the internal market without discouraging the investment required for its modernization.
The acquisition could therefore become a practical test of Europe's evolving economic doctrine.
The central question is no longer simply who owns European companies. It is under what conditions the actors of the global economy may deploy their financial, industrial, and technological power within the European market.
And within this emerging framework, permission to acquire no longer necessarily means unrestricted freedom to integrate.
Main Sources
European Commission — November 3, 2026. Conditional approval of JD.com's acquisition of Ceconomy under the Foreign Subsidies Regulation. Documentation concerning competitive concerns and accepted commitments.
Ceconomy — November 3, 2026. Official announcement concerning the final regulatory clearance required for the transaction and the expected closing timetable.
Reuters — November 3, 2026. Reporting on the European authorization, transaction valuation, and associated commitments.
European Union — Regulation (EU) 2022/2560 of December 14, 2022. Regulation on foreign subsidies distorting the internal market.
European Commission — Foreign Subsidies Regulation. Institutional documentation concerning notification requirements, investigations, distortion assessments, and corrective measures.
JD.com and Ceconomy — July 2025. Corporate announcements concerning the acquisition offer and the initial proposed price of €4.60 per share.
Atlas Limits Research Desk
Atlas Limits’ editorial and analytical desk.